Using Your VA Loan to Buy in Harveston Temecula When the Appraisal Falls Short
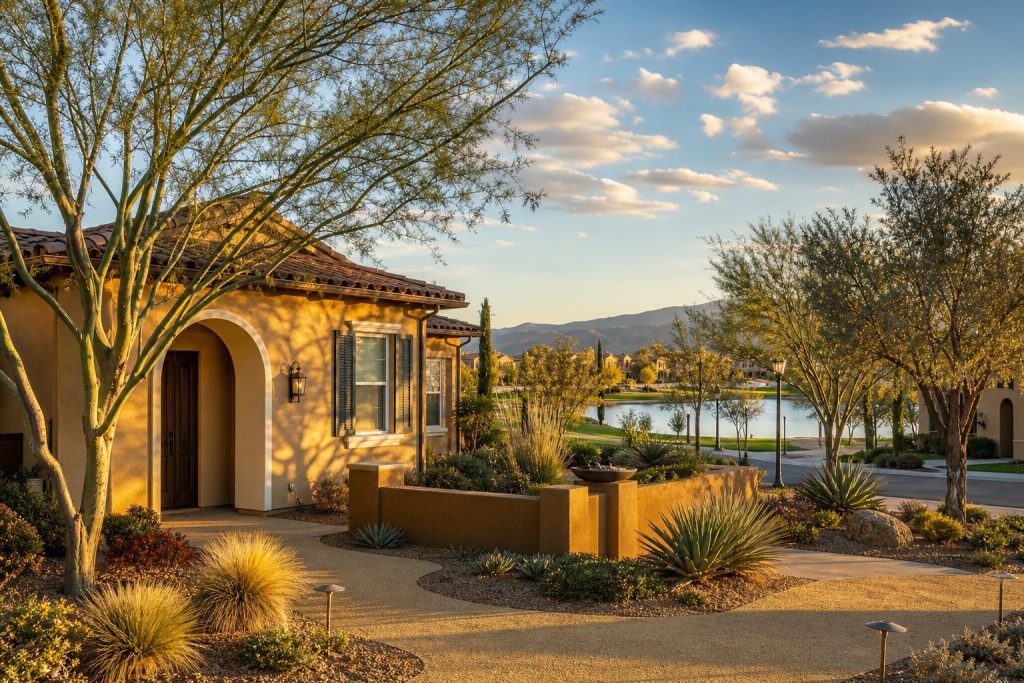
Can you actually use your VA loan benefit to buy a home in Harveston, Temecula, in 2026 if the seller is asking above the VA appraisal limit and you have no cash to cover the gap?
Yes, you can still use your VA loan in Harveston, but if the appraisal comes in below the contract price and you have zero cash to bridge that gap, you will need to negotiate the seller down, challenge the appraisal, or walk away protected by your VA escape clause.
Why This Question Matters for Harveston Buyers in Temecula Right Now
Here is what I see happening in the Temecula market. Homes in Harveston are selling at a median of $802,000 as of the three months ending September 2026, according to local MLS tracking data, with prices up 3.5% year-over-year. At the same time, the broader Temecula market has softened. Homes are sitting closer to 80 days on market versus roughly 40 the year before, per Resideline data. Sellers have lost some leverage.
That combination creates a very specific problem for you as a VA buyer in Harveston. The community holds its value well because of the lake, the schools, and the lifestyle. But when a seller prices a home based on what they *want* rather than what comps support, the VA appraiser may disagree. And if you are putting zero down (one of the greatest benefits of your VA loan), you have no cash cushion to absorb that difference.
A cloudy mind can’t make decisions, so let me walk you through exactly what happens and what your options are.
How the VA Appraisal Works When You Buy in Harveston Temecula
The VA does not set a maximum purchase price. That is a common misconception. With full entitlement, there is no loan cap for VA buyers. What the VA *does* require is an independent appraisal to confirm the home’s fair market value.
If you are under contract on a home in Harveston listed at, say, $779,000, and the VA appraiser determines it is worth $740,000, the VA will only guarantee financing up to $740,000. That $39,000 difference is the “appraisal gap,” and it becomes your problem to solve.
What makes Harveston tricky is the range of property types within the community. Per local listing data, homes in Harveston range from approximately $500,000 for attached townhomes in the Savannah at Harveston sub-community up to over $1.1 million for larger homes near the lake. The VA appraiser has to find comparable sales within a tight geographic and timeframe window, and comparable sales can vary significantly between Harveston’s detached single-family homes and its attached townhome products.
Having closed over 275 transactions across San Diego County and the surrounding areas over 18 years, I can tell you that the appraisal step is where most VA transactions either succeed or stall. It is not random. It is manageable if you prepare for it.
Your Real Options in Harveston Temecula When the Appraisal Comes in Low and You Have No Cash
Option 1: Negotiate the Seller Down to the Appraised Value
This is the most common resolution, and the current market is working in your favor. According to Resideline market data, the seller concession rate across Temecula is 41.3%, up from 39.4%. The sale-to-list ratio sits at roughly 99%. Sellers are adjusting.
What I tell my clients is this: a seller who has been on the market for 60 or 70 days is far more likely to meet the appraised value than a seller who just listed last week. Timing your negotiation matters.
In Harveston specifically, homes sell after an average of 30 days on the market, according to local MLS data, which is faster than the broader Temecula average. That means Harveston sellers may have slightly more leverage. But if a home has sat longer than that 30-day average, your negotiation position strengthens significantly.
Option 2: Use the VA Tidewater Procedure
This is a tool many VA buyers do not even know exists. Before the appraiser finalizes a value below the contract price, they are required to invoke the “Tidewater” process. This notifies your lender, who then has 48 hours to submit additional comparable sales data that might support a higher value.
This is where having an experienced agent matters. I maintain detailed knowledge of recent Harveston sales, including properties like the 40122 Stowe Road sale at $730,000 and the 40153 Medford Road sale at $820,000 (both per MLS closed sale records). Submitting the right comps during Tidewater can shift the appraised value enough to close the gap entirely.
Option 3: Request a Formal Reconsideration of Value
If Tidewater does not resolve it, your lender can submit a formal Reconsideration of Value (ROV) to the VA after the appraisal is finalized. This includes additional comparable sales or corrections to factual errors the appraiser may have made, such as using the wrong square footage or missing a recent renovation.
Option 4: Accept Gift Funds to Cover the Gap
VA loans allow gift funds from family members, friends, or employers. The donor provides a gift letter confirming no repayment is expected. If a family member can help bridge a $20,000 or $30,000 gap, your VA purchase stays on track.
Option 5: Walk Away Using the VA Escape Clause
Every VA purchase agreement includes a mandatory “Amendatory Clause” (also called the VA escape clause). If the appraisal comes in below the contract price and you cannot or choose not to cover the difference, you can walk away and get your earnest money deposit back. No penalty. This protects you from being locked into an overpriced purchase.
What I tell my VA clients is to view this clause as your safety net, not your Plan A. It is there so you never feel pressured into a bad deal.
Why First-Time Buyers and Veterans Should Consider Harveston in Temecula
Harveston is the only lake community in all of Temecula Valley. That is not marketing language; it is a genuine one-of-a-kind feature in the entire Inland Empire. The 17-acre Harveston Lake Park includes a walking loop, paddle boats, a gazebo, picnic areas, and a boathouse that hosts community events. The 19-acre sports park has baseball and soccer fields.
The schools are a major draw. Ysabel Barnett Elementary, located right on Harveston Drive, holds a 9/10 GreatSchools Rating and an A grade on Niche. James L. Day Middle School and Chaparral High School both earn A-range grades on Niche. The entire K-12 pipeline is walkable from most Harveston homes.
For veterans, Temecula’s proximity to Camp Pendleton (roughly 30 miles) and March Air Reserve Base (roughly 25 miles) makes it a natural landing spot. Per World Population Review data, approximately 1,463 Temecula residents are in the Armed Forces, representing about 1.57% of the working-age population.
For first-time buyers, the down-payment math is straightforward:
- VA loans: 0% down payment required. You finance 100% of the purchase price, plus the VA funding fee (typically 2.15% for first-time use) can be rolled into the loan.
- FHA loans: 3.5% down payment minimum with a credit score of 580 or higher.
- Conventional loans: Typically 5% to 20% down, depending on your lender and credit profile.
At Harveston’s entry-level price point of roughly $500,000 to $620,000 for attached townhomes and condos, a VA buyer could purchase with zero down. An FHA buyer would need approximately $17,500 to $21,700 for the down payment alone.
Harveston sits just east of I-15 and south of Winchester Road, one of Temecula’s main commercial corridors, so grocery stores, restaurants, and shopping are all close by. The community itself was designed around shared spaces, with paseos, bike lanes, and tree-lined streets connecting neighbors in a way that feels more like a small town than a typical subdivision.
How an Experienced Real Estate Agent in Temecula Protects Your VA Offer
Working with a VA buyer requires a different playbook than a conventional transaction. As a Broker Associate with 18 years of experience, DRE license 01509668, and 275 five-star client reviews (rated 5 out of 5 by past clients), I bring a few things to the table that directly address the appraisal-gap risk:
- Pre-offer comp analysis. Before you write an offer on a Harveston home, I run my own comparable sales analysis to estimate where the VA appraisal is likely to land. This prevents you from offering a price that is almost certain to create a gap.
- Tidewater preparation. I compile supporting comps in advance so we are ready to respond within the 48-hour Tidewater window rather than scrambling.
- Complimentary attorney contract review. Every buyer I work with receives a complimentary attorney review of contracts and disclosures, covered by me, even if escrow cancels. That extra layer of protection is especially valuable when navigating VA-specific clauses and contingencies.
- Seller negotiation strategy. Presenting a VA offer in a way that reassures the seller about timelines and certainty of close is a skill. Many sellers are hesitant about VA offers because of past stigma. Part of my job is making your offer look as strong as it is.
Frequently Asked Questions About VA Loans in Harveston Temecula
Is there a maximum purchase price for a VA loan in Harveston?
No. If you have full VA entitlement, there is no loan limit. You can purchase at any price point in Harveston. The VA will guarantee financing up to the appraised value, so the appraisal is the critical number, not an arbitrary price cap.
What is the VA funding fee for a first-time VA buyer in 2026?
The VA funding fee for first-time use with 0% down is typically 2.15% of the loan amount. This can be financed into the loan, so you do not need to pay it out of pocket at closing. Some veterans are exempt from the funding fee entirely based on disability status.
Can a seller refuse my VA offer because of the appraisal clause?
A seller can choose any offer they want. However, in a market where homes in Temecula are sitting closer to 80 days on market, per Resideline data, turning away a qualified VA buyer is increasingly risky for sellers. A strong agent can present your offer in a way that addresses seller concerns.
What happens during the VA Tidewater process?
Before finalizing a low appraisal, the VA appraiser notifies the lender, giving your team 48 hours to submit additional comparable sales or relevant data. This is your first opportunity to prevent a low appraisal from becoming final.
Can I use gift money to cover an appraisal gap on a VA loan in Harveston?
Yes. VA loans allow gift funds from family members, friends, or employers. The donor must provide a signed gift letter confirming no repayment is expected. This is one of the clearest paths to closing the gap if you have no personal cash.
What is the VA escape clause?
The VA Amendatory Clause (escape clause) is a mandatory part of every VA purchase contract. It states that if the appraised value is lower than the contract price, you can cancel the contract and receive your earnest money deposit back without penalty.
How much do entry-level homes cost in Harveston Temecula in 2026?
Attached townhomes and condos in the Savannah at Harveston sub-community range from approximately $500,000 to $620,000. Smaller detached single-family homes range from $700,000 to $780,000, per local listing and MLS data.
Do I need any down payment at all with a VA loan?
No. The VA loan allows 0% down payment. You finance 100% of the appraised value. The VA funding fee can also be rolled into the loan. This is one of the most powerful homebuying benefits available.
Are Harveston condos and townhomes eligible for VA loans?
VA loans can be used on condos and townhomes, but the project (or the specific building/association) needs to meet VA approval requirements. It is important to verify this early in your search, especially for properties in the Savannah at Harveston sub-community.
How long are homes in Harveston sitting on the market in 2026?
According to local MLS data, homes in Harveston sell after an average of 30 days on the market, which is faster than the broader Temecula average. However, properties that do not get offers quickly may sit longer, and those are often the best candidates for VA buyer negotiations.
The Bottom Line on Buying in Harveston Temecula With a VA Loan in 2026
Your VA loan benefit is one of the most powerful homebuying tools available, and yes, you absolutely can use it in Harveston. The appraisal gap is a real challenge, but it is not a dead end. Negotiating the seller down, using Tidewater and ROV tools, accepting gift funds, or exercising your VA escape clause all keep you in control.
Harveston’s lake, schools, community feel, and proximity to military installations make it a natural fit for veterans. If you are ready to start the process or just want clear answers about your specific situation, reach out to me directly. I am Scott Cheng, Broker Associate at REAL Brokerage, and I can be reached at 858-405-0002. Let’s build a plan that makes sense for you.