Using Your VA Loan to Buy a Home in Coronado San Diego in 2026
Can I use my VA loan benefit to buy a home in Coronado, San Diego in 2026 if the purchase price exceeds the VA conforming loan limit, and do I need a down payment?
Yes, if you have full VA entitlement, you can purchase a home in Coronado at any price point with zero down payment. The VA eliminated loan limits for full-entitlement borrowers on January 1, 2020, under the Blue Water Navy Vietnam Veterans Act.
Why This Matters for Coronado Buyers Right Now
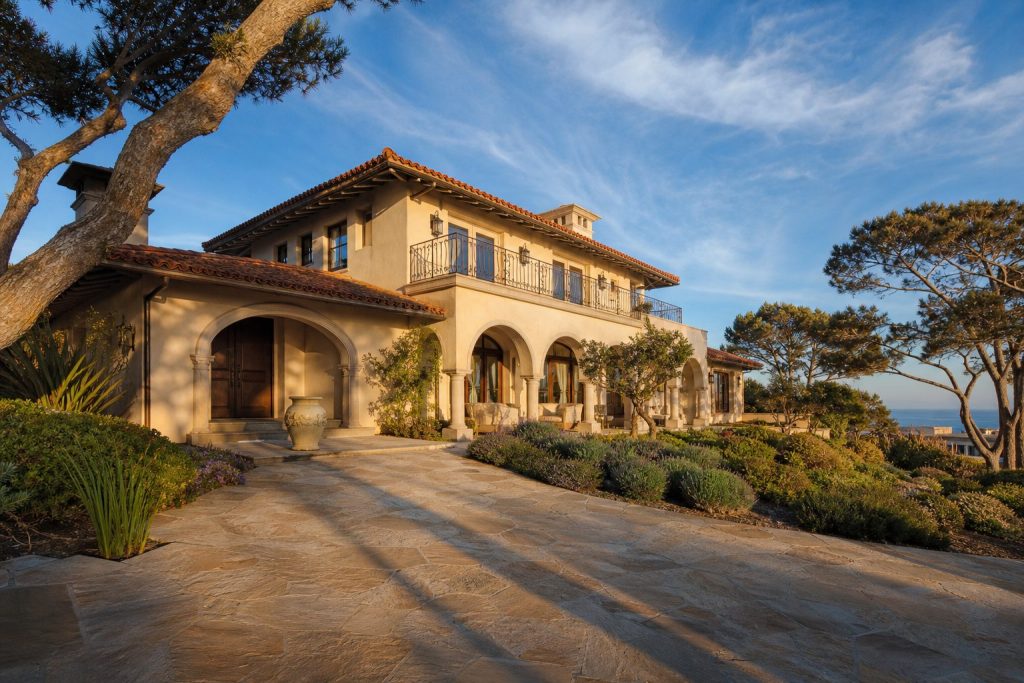
Coronado sits right next to Naval Air Station North Island, making it one of the most sought-after neighborhoods for Navy families in all of San Diego. But Coronado’s home prices are well above the 2026 conforming loan limit of $1,104,000 for San Diego County, per FHFA conforming loan limit guidance. The median home price in Coronado is approximately $2.1 million as of 2026, and the average sale price reached $3,860,113 in Q1 2026, according to San Diego MLS closed transaction data.
That price gap leads many military buyers to assume they’re priced out or that they’ll need a massive down payment. In my 18 years as a real estate broker in San Diego, I’ve seen too many service members walk away from Coronado before they even explore their options. A cloudy mind can’t make decisions, so let me bring you the clean information you need.
Full VA Entitlement Means No Loan Limit in Coronado
Here’s the part that surprises most buyers: if you have your full VA entitlement, there is no cap on how much you can borrow with a VA loan. Not $806,000. Not $1,104,000. No cap at all.
The Blue Water Navy Vietnam Veterans Act, which took effect January 1, 2020, removed VA loan limits for borrowers with full entitlement. This means you can buy a $2 million home in Coronado, or a $3 million home, with zero down payment, as long as you meet the lender’s income and credit requirements and the home appraises at the purchase price.
What “Full Entitlement” Actually Means
You have full entitlement if you meet either of these conditions:
- You’ve never used your VA loan benefit before
- You’ve used it previously but fully paid off and sold the property (your entitlement was restored)
So what does this look like in practice? If you’re an active-duty O-4 stationed at NAS North Island with no existing VA loan, you can use your full entitlement to purchase a Coronado home at virtually any price point. Your lender will qualify you based on your income, your debt-to-income ratio, and the appraised value of the home. The VA’s role is to guarantee the loan, not to limit the amount.
Having closed over 275 transactions in San Diego, many of them with military buyers, I can tell you this one piece of information changes the conversation entirely for families looking at Coronado.
When a Down Payment Is Required: Partial Entitlement in San Diego
Now, here’s where it gets more nuanced. If you have partial entitlement, the 2026 San Diego County conforming loan limit of $1,104,000 comes back into the math.
You have partial entitlement if:
- You currently have an active VA loan on another property (for example, a home you kept as a rental after a PCS)
- You had a prior VA loan that resulted in a loss, such as a foreclosure or short sale where the VA paid a claim
How the Down Payment Calculation Works
With partial entitlement, your remaining VA guarantee covers 25% of the $1,104,000 county limit, minus whatever entitlement you’ve already used. For the portion of the purchase price that exceeds what your remaining entitlement can cover, you’ll need a 25% down payment on the difference.
Here’s what that looks like for a Coronado purchase:
- Scenario: Buying a $2.1M home with partial entitlement – You’d calculate ($2,100,000 minus $1,104,000) times 25%, which equals a $249,000 down payment on the amount exceeding the county limit.
- Scenario: Buying a $1.0M Coronado Shores condo with full entitlement – $0 down payment required. You’re under the county limit, and you have full entitlement. Straightforward.
- Scenario: Buying a $1.5M home with full entitlement – Still $0 down payment. Full entitlement means no limit applies, even though the price exceeds the $1,104,000 conforming limit.
The takeaway? Your entitlement status is the single most important factor. Before you even start browsing Coronado listings, verify your entitlement status through your Certificate of Eligibility.
VA Funding Fee and What It Means at Coronado Price Points
One cost you will want to plan for is the VA funding fee. For first-time VA loan users putting $0 down, the fee is 2.15% of the loan amount, per VA guidelines. On subsequent use, it’s 3.3% with $0 down. The good news: you can finance this fee directly into the loan.
What does that look like at Coronado prices?
- $2.1M purchase, first use, $0 down – Funding fee of approximately $45,150
- $2.1M purchase, subsequent use, $0 down – Funding fee of approximately $69,300
- Putting 5% or more down – Fee drops to 1.5%
- Putting 10% or more down – Fee drops to 1.25%
Here’s the part I always make sure my clients understand: if you have a service-connected disability rating, if you’re a Purple Heart recipient, or if you’re a surviving spouse receiving Dependency and Indemnity Compensation, you are exempt from the funding fee entirely. At San Diego price points, that exemption can save you $20,000 to $30,000 or more.
Practical Challenges VA Buyers Face in Coronado
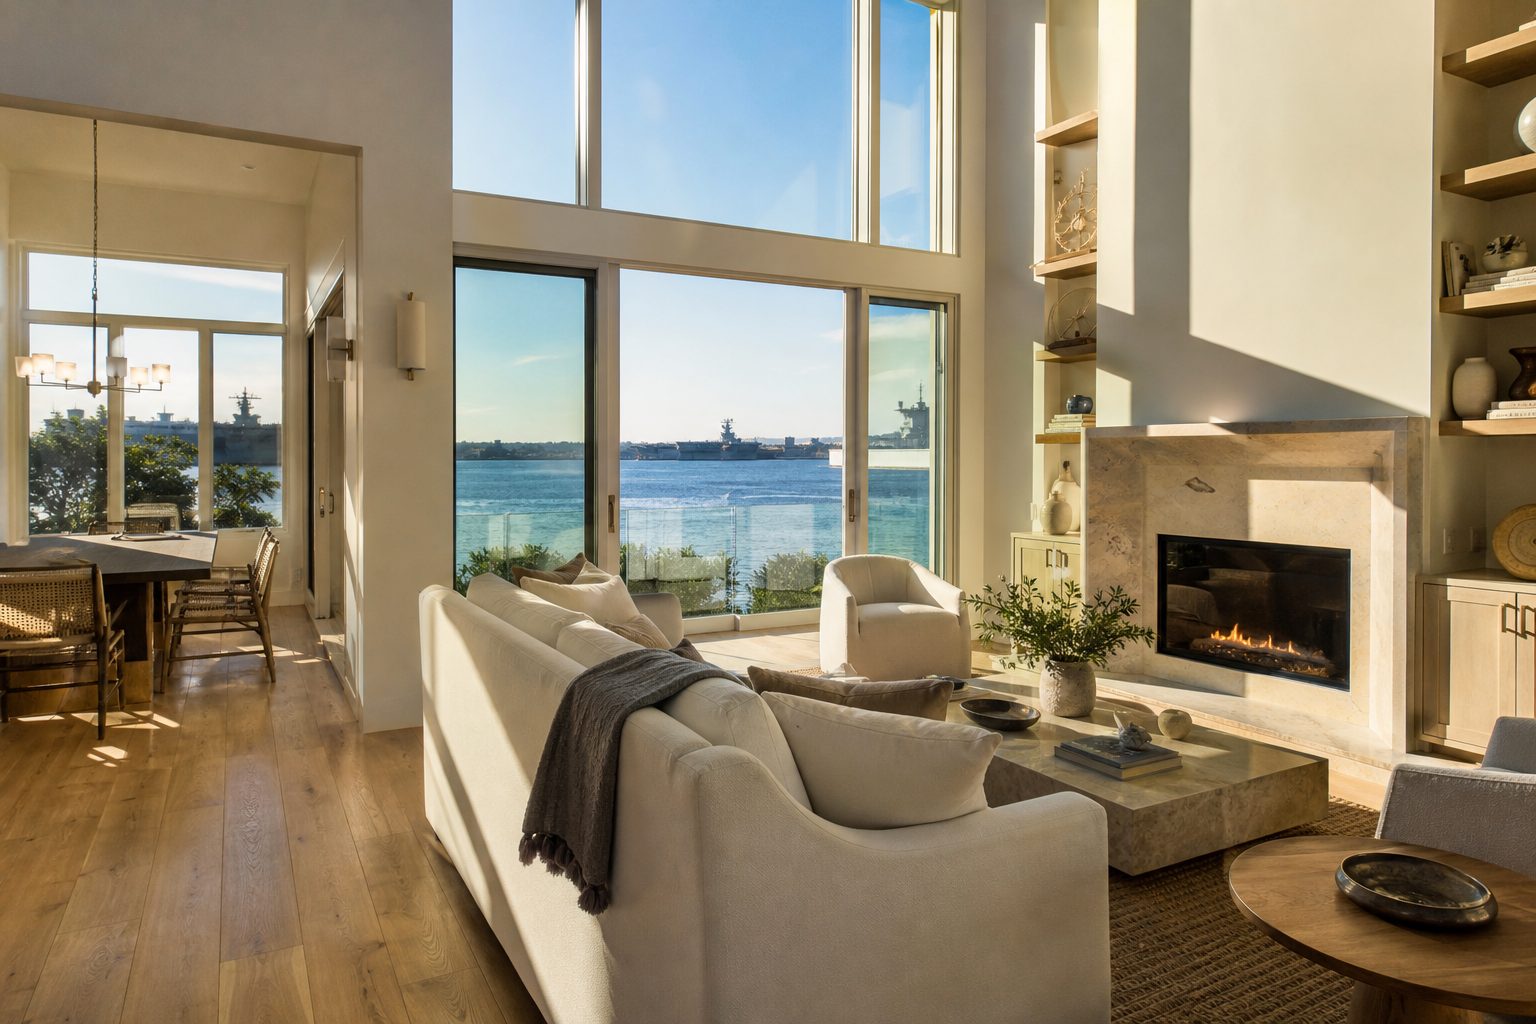
Even with no loan limit and zero down, Coronado’s luxury market presents some real-world considerations that I help my military clients navigate.
VA Appraisal in a Luxury Market
The property must appraise at or above the purchase price. In Coronado, where comparable sales can vary significantly between oceanfront estates and village condos, appraisal gaps are a legitimate concern. If the appraisal comes in low, you’ll need to renegotiate the price, cover the gap out of pocket, or walk away.
VA Minimum Property Requirements
VA appraisals are more thorough than conventional appraisals. The appraiser evaluates safety, structural soundness, and sanitation. Some older Coronado homes may need repairs to meet VA Minimum Property Requirements before the loan can close. This is something I identify early in the process so there are no surprises at the finish line.
Condo Approval Status
Not all condominiums in Coronado are on the VA-approved list. If you’re considering a Coronado Shores unit or another condo complex, you need to verify VA condo approval before writing an offer. This is a step I always confirm before my buyers invest time in a property.
Seller Perception
In Coronado’s luxury market, some sellers and listing agents are less familiar with VA loans at higher price points. The truth is, VA loans over $1.5 million have been successfully closed in San Diego communities including La Jolla, Carlsbad, and Encinitas, per San Diego MLS records. With 275 five-star reviews and the experience of working through 275 closed transactions, I know how to present VA-backed offers with confidence and credibility so sellers take them seriously.
How to Restore Your Entitlement Before Buying in Coronado
If you currently have partial entitlement but want full entitlement for a Coronado purchase, you have options. VA loan entitlement is reusable. Once you pay off an existing VA loan through a sale or refinance, your full entitlement is restored. You can also hold two VA loans simultaneously during a PCS, which is common among military families rotating through San Diego.
What I tell my clients is to start this conversation early. Restoring entitlement or coordinating a sale at your previous duty station takes time, and the earlier we plan, the smoother the transition into a Coronado home.
Frequently Asked Questions
Is there a VA loan limit in San Diego County in 2026?
Only if you have partial entitlement. For borrowers with full VA entitlement, there is no loan limit anywhere in the country as of the Blue Water Navy Vietnam Veterans Act, effective January 1, 2020. With partial entitlement, the 2026 San Diego County conforming loan limit is $1,104,000, per FHFA 2026 conforming loan limit announcement.
Do I need a down payment to buy a home in Coronado with a VA loan?
Not if you have full entitlement. You can purchase at any price point with $0 down as long as you qualify financially and the home appraises. With partial entitlement on a purchase above $1,104,000, you’ll need 25% down on the amount exceeding your remaining entitlement coverage.
What is the median home price in Coronado in 2026?
The median home price in Coronado is approximately $2.1 million as of 2026, with the average sale price reaching $3,860,113 in Q1 2026 according to San Diego MLS closed transaction data. Coronado Shores condos start around $1 million.
Can I finance the VA funding fee into my Coronado home loan?
Yes. The VA funding fee can be rolled directly into your loan amount. For first-time VA loan use with $0 down, the fee is 2.15% of the loan amount, per VA guidelines. Veterans with a service-connected disability are exempt from this fee entirely.
How do I check if I have full or partial VA entitlement?
Request your Certificate of Eligibility through the VA’s eBenefits portal or ask your lender to pull it electronically. The COE will show your total entitlement, any entitlement currently in use, and your remaining available entitlement.
Are Coronado condos VA-approved?
Not all of them. VA loan eligibility for condos requires the complex to be on the VA-approved list. Always verify approval status before making an offer. I check this as a standard step for every condo my military buyers consider.
What income do I need to qualify for a VA loan in Coronado?
It depends on the purchase price and your existing debts. For a $1,104,000 loan at roughly 7% interest with a 43% maximum debt-to-income ratio, you’d need approximately $245,000 to $260,000 in annual gross income assuming minimal other debts, per lender qualification guidelines. Higher purchase prices require proportionally higher income.
Can I use my VA loan more than once?
Absolutely. VA loan entitlement is reusable with no lifetime limit. Once you pay off a VA loan through sale or refinance, your full entitlement is restored. You can also hold two VA loans simultaneously during a PCS move.
Will sellers in Coronado accept a VA loan offer?
Yes, especially when the offer is presented professionally with strong pre-approval documentation. VA loans at higher price points have closed successfully in San Diego luxury markets. Working with a real estate broker who specializes in VA loan real estate transactions for veterans makes a significant difference.
What is the BAH rate for San Diego in 2026?
BAH for an E-5 with dependents in San Diego is approximately $3,465 per month, per current military housing allowance schedules. Higher-ranking officers receive proportionally more, which can expand purchasing power significantly.
The Bottom Line
If you have full VA entitlement, you can absolutely buy a home in Coronado in 2026 with zero down payment, regardless of how far the price exceeds the $1,104,000 conforming loan limit. The key is verifying your entitlement status, getting pre-approved with a VA-experienced lender, and working with a San Diego real estate broker who understands how to navigate VA transactions at higher price points.
I’m Scott Cheng, Associate Broker with REAL Brokerage, DRE# 01509668. With 18 years of experience in San Diego real estate, I offer every buyer a complimentary attorney contract review, covered by me even if escrow cancels. If you’re a veteran or active-duty service member exploring Coronado, I’d welcome the chance to walk you through your options with clarity and no pressure. Reach me at 858-405-0002 or visit my office at 16516 Bernardo Center Dr. Ste. 300.