FHA Loan Qualification in Barrio Logan San Diego with a Credit Score Under 620
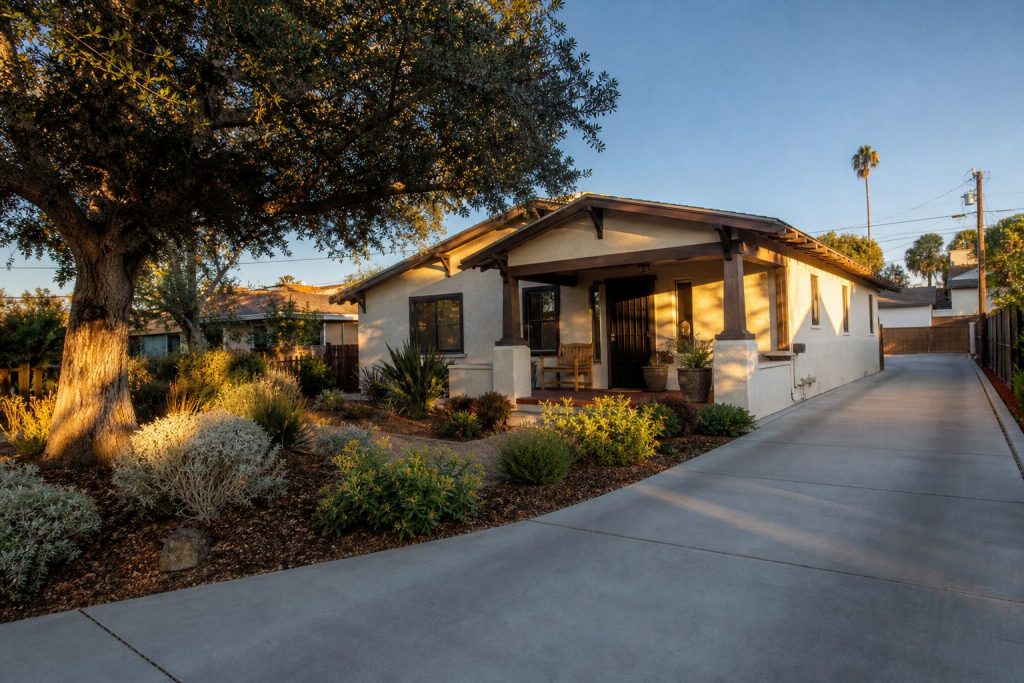
Can you actually qualify for an FHA loan to buy a home in Barrio Logan, San Diego, in 2026 with a credit score under 620 and student loan debt still on your record?
Yes, you can qualify. FHA guidelines allow credit scores as low as 580 for 3.5% down, and student loan debt does not disqualify you, though it does affect your debt-to-income ratio. The real challenge is finding a lender who honors that floor.
Why This Matters Right Now in Barrio Logan
Here is the reality: Barrio Logan sits at a median home value around $662,889 to $735,000, according to multiple market data sources. That is roughly 30 to 40 percent below the San Diego County single-family median of $1,099,500 reported by the California Association of Realtors as of July 2026. For a first-time buyer navigating a credit score under 620 and carrying student loans, Barrio Logan is one of the few urban San Diego neighborhoods where FHA financing can realistically work.
In 2026, San Diego adopted the Barrio Logan Community Plan, the city’s first plan with strengthened anti-displacement protections and enhanced affordable housing requirements. That kind of civic investment signals long-term stability, which matters when you are buying your first home and want to feel confident about where the neighborhood is headed.
So let me walk you through what qualification actually looks like, step by step.
What the FHA Credit Score Rules Really Mean for Barrio Logan Buyers
You have probably seen the headline: FHA allows credit scores as low as 580 for a 3.5% down payment, and scores between 500 and 579 with 10% down. That is the HUD guideline, and it is accurate. But there is a gap between what the program allows and what lenders actually approve.
Most FHA-approved lenders apply their own overlays, typically requiring a 620 to 640 minimum, even though the program technically allows 580. According to approval data, the average credit score for FHA borrowers in 2026 is approximately 685 (per refiguide.org). About 80% of approved FHA borrowers carry scores of 600 or above, and roughly 13% fall in the 550 to 599 range.
What does that mean for you? If your score sits between 580 and 619, you are not disqualified by the program. You just need to shop strategically. Credit unions and smaller community lenders are more likely to honor FHA’s actual minimums. What I tell my clients is this: a denial from one lender does not mean the program is closed to you. It means that lender’s overlay did not fit. Having helped first-time buyers through over 275 transactions in San Diego, I have seen how much the right lender match matters.
If your score is below 580 but above 500, FHA technically permits a 10% down payment. However, only about 2% of FHA loans are approved for borrowers with scores between 500 and 549, so the path is narrow.
How Student Loan Debt Affects Your FHA Qualification in San Diego
Student loans do not disqualify you from an FHA loan. But they absolutely change the math. Here is how.
Active Repayment vs. Deferment
Per HUD Handbook 4000.1, the governing FHA guideline document, student loans in active repayment are counted at their actual monthly payment amount. If your loans are in deferment or forbearance, FHA uses 0.5% of the outstanding loan balance as the assumed monthly payment.
That distinction is significant. If you owe $50,000 in student loans and they are deferred, FHA adds $250 per month to your debt obligations, even though you are not currently paying anything. If you are on an income-driven repayment plan with a documented payment of $120 per month, that lower figure can be used instead.
The DTI Calculation You Need to Understand
FHA’s standard debt-to-income limits are 31% for housing costs (front-end) and 43% for all debts including student loans (back-end). With compensating factors like cash reserves or stable long-term employment, some lenders will stretch that back-end ratio to 50% or higher on a case-by-case basis, per multiple lending sources.
But here is the catch for buyers under 620: you will likely face manual underwriting, which typically caps you at 31/43 without compensating factors. That tighter cap makes your student loan payment, whether actual or calculated, a critical piece of the puzzle.
A cloudy mind can’t make decisions, so let me make this concrete. If your gross monthly income is $7,500, a 43% back-end DTI means your total monthly debts (including your future mortgage payment, student loans, car payment, and credit cards) cannot exceed $3,225. Every dollar of student loan obligation compresses the room available for your mortgage.
What an FHA Purchase Actually Costs in Barrio Logan in 2026
Let me put real numbers in front of you so this stops being abstract.
Down Payment
At 3.5% down on a $662,889 home (the approximate Barrio Logan median value per market data), your minimum down payment would be about $23,201.
FHA Mortgage Insurance
FHA requires a 1.75% upfront mortgage insurance premium (UFMIP) plus annual mortgage insurance premiums (MIP). For borrowers in the 580 to 619 credit range, annual MIP ranges from 0.85% to 0.95%, according to lending data sources. That UFMIP can be rolled into the loan, but it does increase your financed amount.
Interest Rate Expectations
FHA loan rates in 2026 vary by credit tier, per loan.ai data. For scores of 620 and above, rates range from 6.0% to 6.5%. For 600 to 619, expect 6.3% to 6.8%. For 580 to 599, rates climb to 6.5% to 7.0%.
The difference between a 6.3% and a 7.0% rate on a $640,000 loan is roughly $300 per month. That is real money, and it is one reason why improving your score even 20 to 30 points before applying can save you thousands over the life of the loan.
FHA Loan Limits
The 2026 FHA loan limit for San Diego County reaches up to $1,249,125 for a single-family home, per HUD data. Barrio Logan’s price point falls well within that ceiling, so the loan limit will not be a barrier for you.
How to Strengthen Your FHA Application Before You Apply in Barrio Logan
So what can you actually control? More than you might think.
Reduce Your Reported Monthly Debt
If your student loans are deferred, consider switching to an income-driven repayment plan with a lower documented monthly payment. This directly reduces the figure used in your DTI calculation and can significantly expand your purchasing power.
Build Compensating Factors
Manual underwriting (which you will likely face under 620) allows for DTI flexibility when you bring compensating factors to the table. These include three months of cash reserves after closing, minimal payment shock (meaning your new housing payment is close to what you currently pay in rent), and a stable two-year employment history in the same field.
Shop at Least Three Lenders
This is not optional advice. Lender overlays vary dramatically. What I consistently see with first-time buyers in San Diego is that the third lender often has materially different approval criteria than the first two. With 18 years of experience and an FHA loan specialty, I maintain relationships with lenders who honor the program’s actual minimums rather than hiding behind inflated overlays.
Consider the Barrio Logan Condo Market
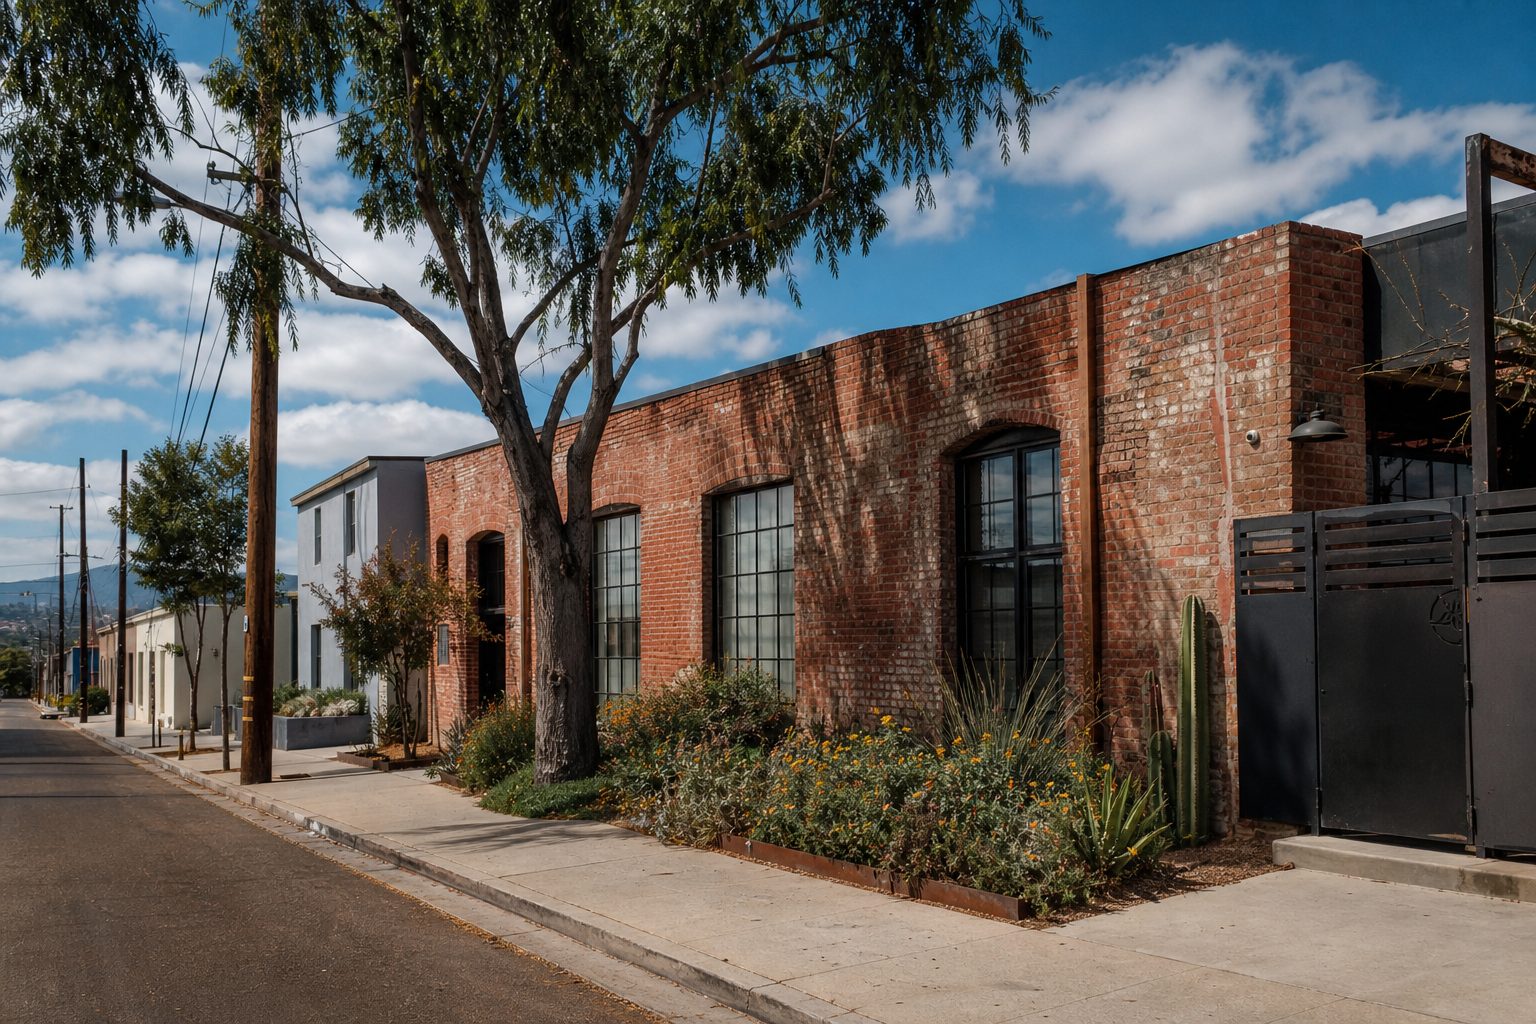
With Barrio Logan’s walkability scores above 80, proximity to Downtown employment, and strong rental demand (approximately 84% renter-occupied per Niche data), condos and townhomes in the area can offer an even more accessible entry point. San Diego’s condo and townhome median sits between $670,000 and $675,000 countywide as of mid-2026, and Barrio Logan often comes in below that.
Why Barrio Logan Makes Strategic Sense for First-Time San Diego Buyers
Beyond affordability, there are structural reasons Barrio Logan works for first-time buyers using FHA financing.
The neighborhood’s emerging arts and maker district identity, walkability, and proximity to both Downtown and the Naval Base create consistent demand. Market data shows approximately 8.3% annual appreciation in Barrio Logan, which suggests the equity-building potential is real, not speculative.
The 2026 Barrio Logan Community Plan, with its enhanced affordable housing replacement requirements, lengthened tenant noticing, and strengthened relocation assistance, creates a neighborhood framework designed to protect residents rather than displace them. That kind of policy environment matters when you are putting roots down.
With 275 five-star reviews and a 5 out of 5 average rating from past clients, I have walked many first-time buyers through exactly this decision. One thing that comes up consistently is the emotional weight of wondering whether you even qualify. You deserve a clear answer before the anxiety builds.
Frequently Asked Questions About FHA Loans in Barrio Logan San Diego
Can I get an FHA loan in Barrio Logan with a 580 credit score?
Yes. HUD guidelines allow a 3.5% down payment with a 580 credit score. However, many lenders impose overlays requiring 620 or higher. You will need to specifically seek lenders who honor the 580 floor, which often includes credit unions and community banks. Shopping multiple lenders is essential.
Does student loan debt disqualify me from an FHA loan?
No. Student loan debt does not disqualify you. It is factored into your debt-to-income ratio. If your loans are in active repayment, the actual monthly payment is used. If deferred, FHA calculates 0.5% of the outstanding balance as your assumed monthly payment per HUD Handbook 4000.1.
What is the maximum debt-to-income ratio for FHA in 2026?
The standard FHA DTI limits are 31% front-end and 43% back-end. With compensating factors and automated underwriting approval, some lenders allow up to 50% or higher. Under manual underwriting (common for scores below 620), you are typically capped at 31/43 without compensating factors.
How much is a down payment on a Barrio Logan home with FHA?
At 3.5% down on the approximate Barrio Logan median of $662,889, your minimum down payment would be roughly $23,201, plus closing costs. Down payment assistance programs may reduce your out-of-pocket requirement.
What are FHA interest rates for credit scores under 620 in 2026?
Per 2026 lending data from loan.ai, FHA rates for borrowers with scores between 600 and 619 range from 6.3% to 6.8%. For scores between 580 and 599, expect 6.5% to 7.0%.
Is Barrio Logan within FHA loan limits for San Diego County?
Yes. The 2026 FHA loan limit for San Diego County is up to $1,249,125 for a single-family home, per HUD data. Barrio Logan’s median home values fall well within this ceiling.
What is FHA mortgage insurance and how much does it cost?
FHA requires a 1.75% upfront mortgage insurance premium (which can be financed into the loan) plus an annual MIP. For borrowers in the 580 to 619 credit range, annual MIP ranges from 0.85% to 0.95% of the loan amount.
Can I use income-driven repayment to lower my DTI for FHA?
Yes. If you are on an income-driven repayment plan and can document the actual monthly payment amount, FHA allows that figure to be used instead of the 0.5% calculation. This can meaningfully lower your DTI ratio.
What is manual underwriting and will I face it with a score under 620?
Manual underwriting is a process where a human underwriter reviews your file instead of automated software. Borrowers with credit scores below 620 are frequently routed to manual underwriting, which applies stricter DTI caps (typically 31/43) but can be flexible with compensating factors.
Should I wait to improve my credit before buying in Barrio Logan?
It depends on the gap. If you are at 610 and could reach 620 within two to three months through targeted credit repair, waiting may unlock more lender options and a lower interest rate. If you are at 585 and improvement would take a year, it may make sense to pursue FHA now while Barrio Logan’s price point remains accessible, given its appreciation trend.
The Bottom Line
You can qualify for an FHA loan in Barrio Logan, San Diego, in 2026 with a credit score under 620 and student loan debt on your record. The program allows it, the neighborhood’s price point supports it, and the right lender match makes it possible. The key is understanding how your student loans affect your DTI, knowing that manual underwriting applies tighter caps, and shopping lenders who honor FHA’s actual credit score floors.
As a Broker Associate with REAL Brokerage and 18 years guiding San Diego buyers through exactly these decisions, I offer every buyer a complimentary attorney review of contracts and disclosures, covered by me, even if escrow cancels. If you are ready to find out where you stand, call me at 858-405-0002. A clear plan starts with a calm conversation, and that is always free.