Using Your VA Loan in Convoy District San Diego With Second-Tier Entitlement and a Past Foreclosure
Can I use my VA loan benefit to buy a home in Convoy District San Diego in 2026 if I have a second-tier entitlement and a previous foreclosure on my record?
Yes, you can. A prior foreclosure does not permanently disqualify you from using your VA loan benefit. Once the waiting period is satisfied and your remaining entitlement is calculated, buying in Convoy District is absolutely possible, especially given the condo and townhome options in that area.
Why This Matters Right Now in San Diego
Convoy District is undergoing one of the most exciting transformations in all of San Diego. What was once purely a commercial and industrial corridor in Kearny Mesa is becoming a mixed-use neighborhood with new residential development, improved infrastructure, and walkable access to some of the region’s most celebrated restaurants and cultural destinations.
For veterans, this timing matters. San Diego’s 2026 conforming loan limit is $1,104,000, per FHFA data. That is significantly higher than the baseline limit of $832,750 used in most U.S. counties. A higher limit means your remaining second-tier entitlement stretches further here than it would in many other markets.
With 18 years helping buyers navigate San Diego real estate and a specialty in VA loan transactions, I work through second-tier entitlement calculations regularly. A cloudy mind can’t make decisions, so let me walk you through the numbers and what they actually mean for your purchasing power in Convoy District.
How Second-Tier Entitlement Works for Convoy District Buyers
Your VA entitlement comes in two layers. The first is your basic entitlement of $36,000, which covers 25% of a $144,000 loan. The second, your bonus (or second-tier) entitlement, covers the gap between that basic amount and 25% of your county’s conforming loan limit.
In San Diego for 2026, the math looks like this:
- Total available entitlement: $1,104,000 x 25% = $276,000
- Remaining entitlement: $276,000 minus whatever entitlement is still “charged” from your previous VA loan
Here is the key formula: your remaining entitlement multiplied by four equals your maximum zero-down purchase price. So if you have $176,000 in remaining entitlement, you could purchase up to $704,000 with no money down. That figure covers many of the condos and townhomes in the broader Kearny Mesa and Convoy District area, where attached homes in the 92111 ZIP code generally fall in the mid-$500,000s to $800,000+ range.
What does that actually look like day-to-day? It means you are likely not shut out of the Convoy District market. You may have more options than you think.
What a Prior Foreclosure Means for Your VA Loan Eligibility in San Diego
This is the part that trips up most veterans, and understandably so. Having a foreclosure on your record does not erase your VA loan benefit. But it does create a few hurdles you need to clear.
The Waiting Period
The standard VA waiting period after a foreclosure is two years from the date the foreclosure was completed. Some individual lenders apply overlays that extend this to three years or more, which is why working with a VA-experienced lender familiar with San Diego is critical.
Your Charged Entitlement
When the VA paid out a guaranty claim on your foreclosed loan, that amount gets “charged” against your entitlement. It stays charged until either:
- You repay the VA’s loss in full (which would allow full entitlement restoration)
- You use your remaining entitlement as-is, without restoration
If the VA loss has not been repaid, your entitlement is reduced, not eliminated. Your Certificate of Eligibility will show exactly how much entitlement remains available. I always tell my clients that the COE is the first document to request because everything else, your price ceiling, your down payment needs, your lender options, flows from that number.
Credit Requirements After Foreclosure
Most VA lenders in San Diego want to see:
- A minimum credit score of 580 to 620, with many preferring 640 or higher after a foreclosure event
- Evidence that you have re-established credit since the foreclosure
- Sufficient residual income, which varies by family size and region
- A debt-to-income ratio generally at or below 41%, though compensating factors can allow flexibility
The VA Funding Fee and How to Reduce It in Convoy District
Because this would be a subsequent use of your VA loan benefit, you will face a higher funding fee than a first-time VA borrower. Here is how the fee structure breaks down, per the VA’s published schedule:
- Zero down payment, subsequent use: 3.30% of the loan amount
- 5% to 9.99% down, any use: 1.50%
- 10% or more down, any use: 1.25%
On a $670,000 purchase (near the San Diego attached home median of $670,000 as of October 2026, per SDAR), a 3.30% funding fee would add approximately $22,110 to your loan. That is a real number, and it deserves a real conversation.
Here is where it gets interesting. If you have a service-connected disability rating of 10% or higher, you are completely exempt from the funding fee. That exemption alone could save you over $20,000 on a Convoy District purchase. Having closed over 275 transactions in San Diego, I can tell you that many veterans I work with do not realize they qualify for this exemption until we sit down and review their situation together.
Even if you do not have a disability rating, putting just 5% down drops the funding fee significantly. Sometimes a modest down payment is the smarter financial move, and I help clients model both scenarios before they commit.
Convoy District Property Considerations for VA Buyers in 2026
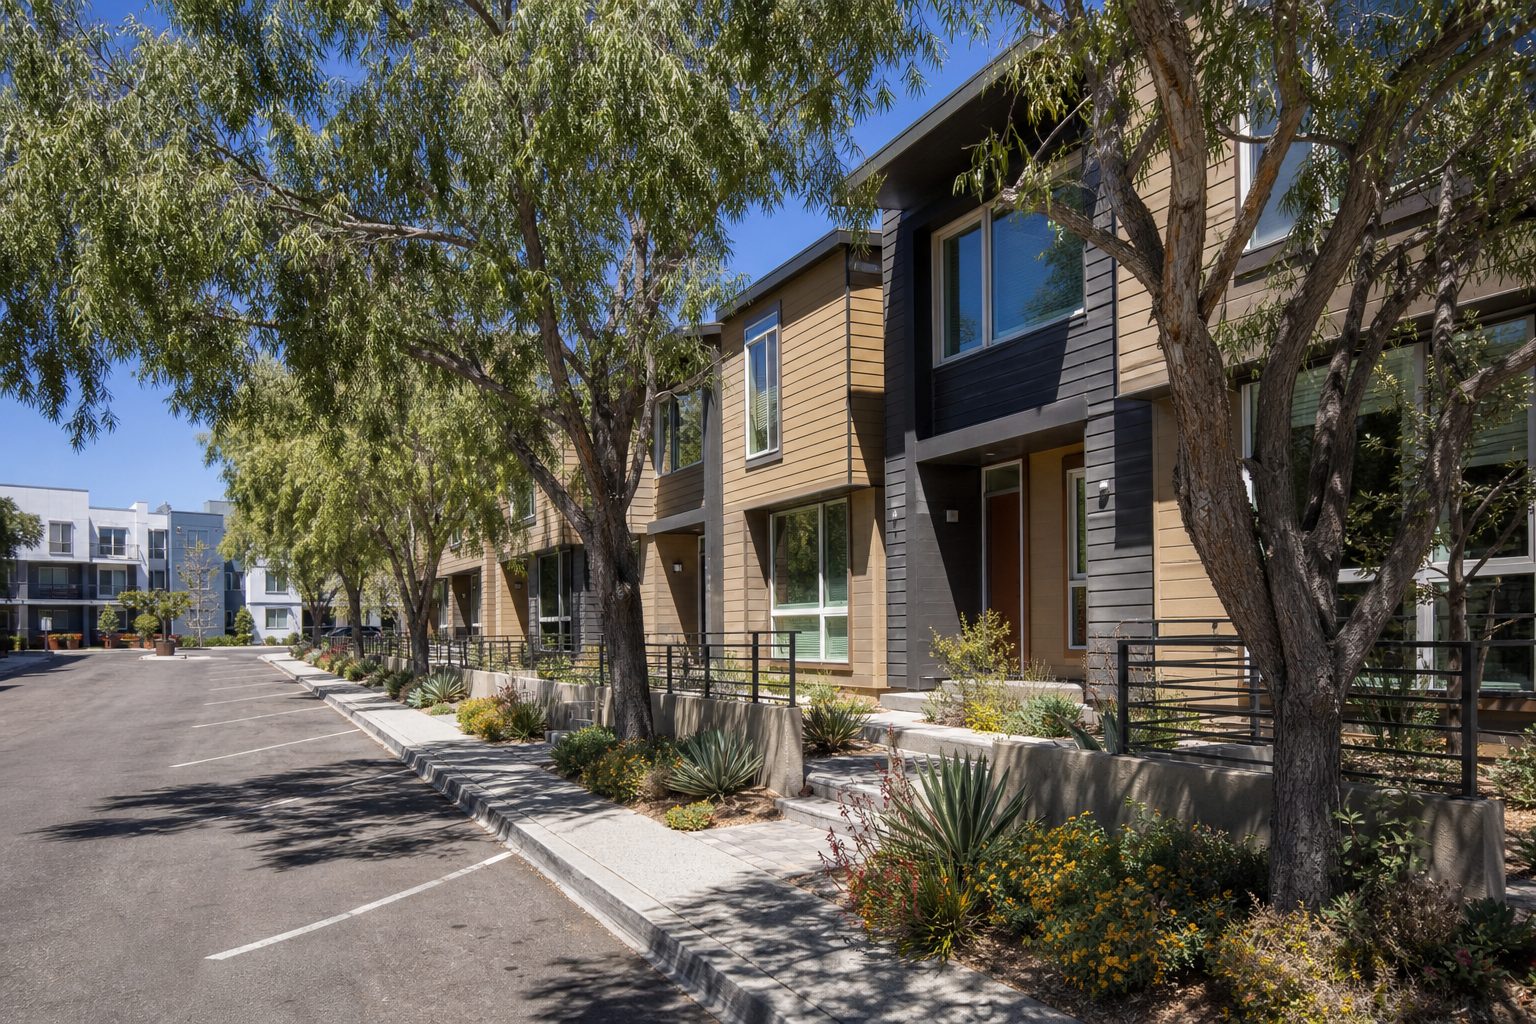
Convoy District sits within Kearny Mesa, and the neighborhood is evolving rapidly. The recently opened Alexan Camellia added 531 residential units directly on Convoy Street, marking the first time residents could actually live on that corridor. The Palmer Kearny Mesa proposal would add another 1,642 units. The Kearny Mesa Community Plan envisions 50,000 new residents, new bike lanes, additional parking, and eventually a trolley line connecting to the rest of San Diego.
So what does this mean for your home search?
Condo Buyers: Check VA Approval Status
If you are looking at a condo in Convoy District, the complex must be on the VA’s approved condo list. Not every project qualifies, and newer developments sometimes take time to receive approval. This is something I verify for my clients before we even schedule a showing, because there is no point falling in love with a unit you cannot finance.
Pricing Context
San Diego County’s overall median home price sits at $910,000 as of October 2026, per SDAR, with attached condos and townhomes at a median of $670,000. Detached single-family homes carry a median of $1,079,000 countywide. The Convoy District and broader 92111 ZIP code tend to offer more accessible price points than coastal neighborhoods, which is exactly why this area attracts veteran buyers looking to maximize their remaining entitlement.
The market remains competitive. As of August 2026, homes in San Diego County sold in a median 28 days and 35.4% sold above list price. That pace demands preparation, not panic.
Step-by-Step Action Plan for Convoy District VA Buyers
If you are a veteran with second-tier entitlement and a prior foreclosure, here is the sequence I walk my clients through:
1. Request your Certificate of Eligibility to confirm your remaining entitlement and any charged amounts 2. Confirm your waiting period by verifying at least two years have passed since foreclosure completion 3. Calculate your zero-down ceiling using the San Diego CLL of $1,104,000 4. Explore entitlement restoration if you have repaid the VA’s loss on the foreclosed loan 5. Get pre-approved with a lender experienced in second-tier entitlement calculations 6. Verify condo VA approval status for any Convoy District complexes you are considering 7. Work with an agent who understands VA timelines to position your offer competitively
Rated 5 out of 5 stars by 275 past clients, I provide every buyer with a complimentary attorney review of contracts and disclosures, covered by me even if escrow cancels. That extra layer of protection matters, especially when the transaction involves entitlement calculations and post-foreclosure documentation.
Frequently Asked Questions
Can I buy a home in Convoy District with zero down using second-tier VA entitlement?
You can, as long as your remaining entitlement multiplied by four equals or exceeds the purchase price. In San Diego, total entitlement is $276,000 (25% of the $1,104,000 conforming loan limit for 2026, per FHFA). Subtract whatever entitlement is charged from your foreclosed loan. The resulting figure times four is your zero-down ceiling.
How long do I have to wait after a VA loan foreclosure to buy again?
The standard VA waiting period is two years from the date the foreclosure was completed. However, individual lenders may impose longer waiting periods as overlay requirements. Working with a VA-specialized lender in San Diego ensures you understand both VA guidelines and lender-specific rules.
Is my VA loan entitlement permanently reduced after foreclosure?
No. Your entitlement is reduced, not eliminated. If you repay the VA’s financial loss from the foreclosure, you may qualify for full entitlement restoration. Without repayment, you use whatever entitlement remains, which is often enough to purchase in the Convoy District price range.
What credit score do I need to use my VA loan after a foreclosure in San Diego?
Most VA lenders require a minimum credit score of 580 to 620 after a foreclosure, though many prefer 640 or higher. You will also need to demonstrate re-established credit, sufficient residual income, and a manageable debt-to-income ratio, generally 41% or below.
How much is the VA funding fee for subsequent use in 2026?
For zero-down subsequent use, the VA funding fee is 3.30% of the loan amount, per the VA’s published fee schedule. Putting 5% down reduces the fee to 1.50%. Veterans with a service-connected disability rating of 10% or higher are completely exempt.
Are condos in Convoy District approved for VA loans?
Not all condos qualify. The complex must appear on the VA’s approved condo list. Newer developments like the Alexan Camellia may or may not have completed the approval process. Always verify before making an offer.
Can I restore my full VA entitlement after a foreclosure?
Yes, if you repay the VA’s loss from the foreclosure in full. Veterans can use their VA guaranteed home loan benefit more than once, and once repaid, you may apply for a one-time restoration of entitlement. With full entitlement restored, there is no county loan limit cap on your VA guaranty.
What is the conforming loan limit in San Diego for 2026?
San Diego’s 2026 conforming loan limit is $1,104,000, per FHFA data. This high-cost designation directly benefits veterans by expanding the entitlement available for purchasing in this market.
Is Convoy District a good area for VA buyers in 2026?
Convoy District offers attached homes at price points often below the countywide median, proximity to MCAS Miramar, walkable amenities, and significant ongoing development. These factors make it a practical target for veterans using second-tier entitlement.
Should I make a down payment even though the VA loan allows zero down?
In many cases, yes. A 5% down payment drops the funding fee from 3.30% to 1.50%, which can save you thousands. I help clients model both scenarios to find the option that makes the most financial sense for their specific situation.
The Bottom Line
A previous foreclosure and second-tier entitlement do not close the door on homeownership in Convoy District. With San Diego’s $1,104,000 conforming loan limit for 2026, your remaining entitlement likely stretches further than you expect, particularly for condos and townhomes in this rapidly evolving neighborhood. The key is knowing your numbers: your remaining entitlement, your zero-down ceiling, and whether entitlement restoration is an option.
If you are a veteran considering Convoy District and you want clear, no-pressure guidance through the entitlement math and lender selection, I am here to help. I am Scott Cheng, Associate Broker with REAL Brokerage, and you can reach me at 858-405-0002 or visit my office at 16516 Bernardo Center Dr. Ste. 300 in San Diego. Let’s build a calm plan you can feel good about.