How to Sell Your Clairemont Home Before Relocating Out of State in 2026
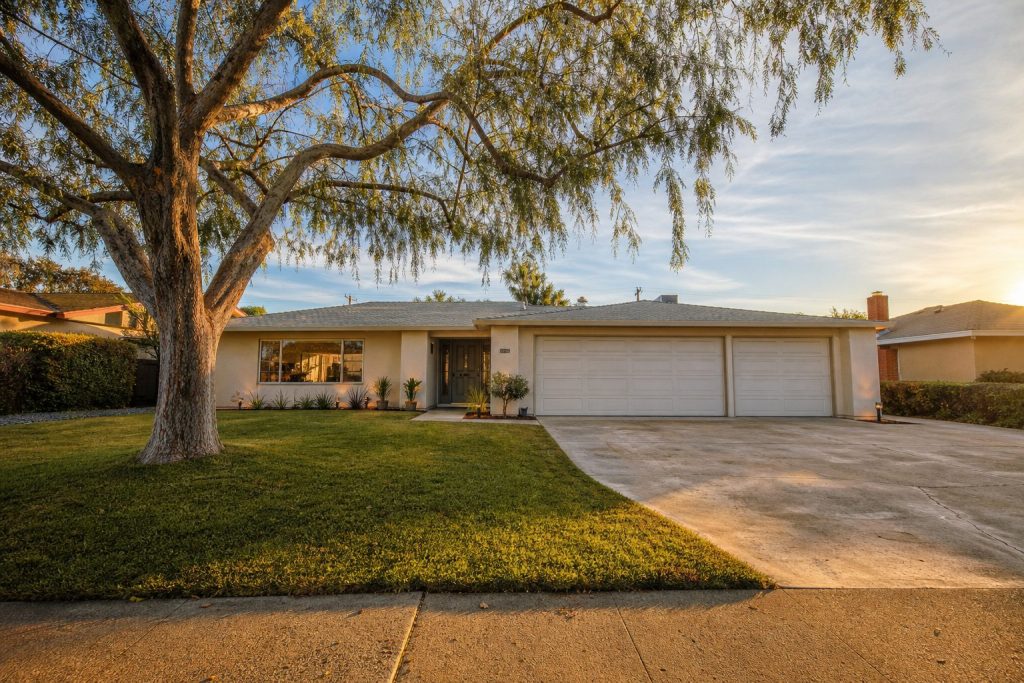
How do I sell my home in Clairemont, San Diego in 2026 before relocating out of state and coordinate the closing date so I’m not stuck paying two mortgages or living in a hotel?
You coordinate by choosing one of several proven strategies: a rent-back agreement, a synchronized closing timeline, or a bridge loan, all built around Clairemont’s tight inventory and fast sale pace in 2026.
Why This Matters Right Now in Clairemont
Clairemont is one of the tightest inventory environments in San Diego County right now. According to the San Diego Association of REALTORS, single-family homes in Clairemont had just 1.2 months of supply as of early 2026, with homes selling in roughly 24 days on average. That speed is your friend if you’re relocating, but only if you plan ahead.
Here’s the real pressure: at today’s mortgage rates of approximately 6.68% as of mid-August 2026 (per Fannie Mae and MBA projections), carrying two mortgages even briefly on a Clairemont home near the $1,142,500 year-to-date median can cost well over $6,000 a month in principal and interest alone. Add property taxes and insurance, and you’re looking at something closer to $7,000 to $8,000 monthly for a house you’re no longer living in.
A cloudy mind can’t make decisions. So let me lay out a clear plan for how to sell your Clairemont home and coordinate your move without financial pain or logistical chaos.
Strategy 1: Negotiate a Rent-Back Agreement on Your Clairemont Home
This is the strategy I discuss most often with relocating clients, and it works especially well in Clairemont’s current market. Here’s how it goes: you sell your home, close escrow, receive your proceeds, and then stay in the property as a renter for a negotiated period, typically 30 to 60 days.
Why does this work so well right now? Because Clairemont buyers are competing for very limited inventory. When supply sits below 1.0 months, as it did in March 2026 according to SDAR data, you have real leverage in negotiations. Buyers who want your home are often willing to agree to a short rent-back because the alternative is losing the deal entirely.
What to Know About the 60-Day Limit
Most conventional lenders, including those following Fannie Mae and Freddie Mac guidelines, allow rent-backs of up to 60 days without reclassifying the property as an investment. Beyond that threshold, the buyer’s financing can get complicated. So if you need more than 60 days, that conversation has to happen early, and your agent needs to structure it carefully.
What I tell my clients is this: a rent-back gives you the best of both worlds. You get your sale proceeds in hand so you can make a strong offer in your destination market, and you avoid scrambling for a hotel or short-term rental in San Diego while you finalize the move.
Strategy 2: Synchronize Your Clairemont Closing with Your Out-of-State Purchase
If your relocation timeline is flexible, you can list your Clairemont home and simultaneously begin your home search in the destination state. Once you accept an offer here, you negotiate a closing date that lines up with your purchase closing out of state.
The math works in your favor in Clairemont. Well-priced homes in the 92117 zip code are selling in 15 to 17 days on average, per local MLS data reported by multiple San Diego brokerages. Add a 30 to 45 day escrow, and your total timeline from listing to closing is roughly 60 to 75 days. That’s a workable window if you start your out-of-state search as soon as your Clairemont listing goes active.
Pricing Is the Key to Controlling the Timeline
Here’s the nuance most sellers miss: your pricing strategy on day one determines how much control you have over the rest of the process. The countywide sale-to-list ratio in 92117 was running at 98.6% as of May 2026 per SDAR data, meaning sellers are landing very close to their asking price. Price it right and you attract offers quickly. Price it high hoping to “test the market,” and you risk sitting past that 21-day threshold where negotiating power begins shifting from seller to buyer.
With 18 years helping San Diego sellers navigate exactly these situations, I can tell you that an extra $10,000 on the list price is rarely worth an extra 30 days on the market when you have a relocation deadline.
Strategy 3: Use a Bridge Loan to Buy Before You Sell in Clairemont
If your job start date or family timeline means you absolutely need to close on your new home first, a bridge loan may be the right tool. This is short-term financing, typically 6 to 12 months, secured by the equity in your Clairemont home.
The math is straightforward for many Clairemont homeowners. With the year-to-date single-family median at $1,142,500 per SDAR data from February 2026, and assuming a remaining mortgage balance somewhere between $400,000 and $600,000, many sellers here have $500,000 or more in equity. A bridge loan on a portion of that equity, say $300,000 at roughly 9%, costs about $2,250 per month. That’s significantly less than carrying an entire second mortgage.
The trade-off is cost, but it buys you something priceless: the ability to make a non-contingent offer in your destination market and move on your own schedule.
Strategy 4: Consider a Cash Sale for Maximum Speed and Certainty
If your timeline is extremely tight, say a corporate relocation with a hard start date in three weeks, a direct cash sale compresses the process dramatically. Cash sales can close in 12 to 24 days total, according to San Diego market transaction data.
The catch? Cash offers typically come in 5 to 15 percent below market value. On a Clairemont home near the $1,142,500 median, that could mean accepting $57,000 to $171,000 less than what you’d get on the open market. For most sellers, that’s too steep a discount. But if avoiding two mortgages or hotel costs is worth more than the price gap, it’s a valid option to evaluate.
What I walk my clients through is the full cost comparison: what does the discount cost you versus what does carrying two mortgages, paying temporary housing, and managing a remote sale cost you? Sometimes the numbers surprise people.
How Clairemont’s 2026 Market Gives Relocating Sellers an Advantage
You’re not selling into a slow market. That matters enormously. In August 2026, ZIP code 92117 recorded 46 home sales, making Clairemont one of the busiest zip codes in the county, according to sdhousingmarket.com. Detached inventory across San Diego County dropped 20.7% year over year in August 2026 per Redfin data, and Clairemont’s sub-areas, including the Mount Streets, North Clairemont, Bay Park, and Bay Ho, are all benefiting from that scarcity.
Clairemont’s housing stock, mostly single-story ranch homes from the 1950s through 1970s on generous lots, continues to attract buyers, investors, and ADU builders. The price per square foot in 92117 is approximately $842, up about 7.3% year over year per local MLS data. That appreciation momentum means your equity position is likely stronger than you think.
Having closed over 275 transactions across San Diego County with a 5 out of 5 star average across 275 client reviews, I’ve seen how Clairemont’s market dynamics specifically favor sellers who plan ahead and price strategically. Your home’s position within the conforming loan limit of $1,104,000 for 2026, or near it, also widens your buyer pool significantly because purchasers can avoid jumbo loan pricing.
Frequently Asked Questions
How long does it take to sell a home in Clairemont in 2026?
Well-priced single-family homes in Clairemont’s 92117 zip code are selling in approximately 15 to 29 days on market, according to SDAR and local MLS data from early to mid-2026. Add a standard 30 to 45 day escrow for financed buyers, and you’re looking at roughly 60 to 75 days from listing to closing for a move-in ready property.
What is a rent-back agreement and how long can it last?
A rent-back lets you stay in your home after closing as a tenant, paying the new owner a daily or monthly rate. Most conventional lenders allow rent-backs up to 60 days. Beyond that, the buyer’s lender may reclassify the property as an investment, which can complicate or kill the deal.
Can I sell my Clairemont home and buy out of state at the same time?
Yes, but it requires careful coordination of closing dates. The approach I recommend is listing your Clairemont home first, securing an offer, then negotiating an escrow timeline that aligns with your out-of-state purchase. In Clairemont’s tight market, you have leverage to negotiate favorable terms.
What is a bridge loan and is it worth the cost?
A bridge loan is short-term financing secured by your current home’s equity, allowing you to buy your next home before selling. Bridge loan rates in 2026 run roughly 8 to 10 percent. For a Clairemont homeowner with significant equity, a $300,000 bridge loan costs about $2,250 per month, often less than carrying two full mortgages.
What are the risks of selling my home before buying?
The primary risk is needing temporary housing if your out-of-state purchase isn’t ready. A rent-back agreement mitigates this. Another risk is making decisions under pressure, which is why having a clear plan and experienced real estate broker in San Diego is critical.
How much equity do Clairemont homeowners typically have in 2026?
With the year-to-date single-family median at $1,142,500 per SDAR data from February 2026, many long-term Clairemont homeowners hold $500,000 or more in equity, depending on their remaining mortgage balance. This equity is what makes bridge loans and HELOCs viable options.
Will I owe capital gains taxes when I sell?
Under IRS Section 121, you can exclude up to $250,000 in capital gains as a single filer or $500,000 as a married couple filing jointly, provided the home was your primary residence for at least two of the last five years. Most relocating homeowners qualify, but consult a tax professional for your specific situation.
Should I stage my Clairemont home before listing?
In a market where the sale-to-list ratio is 98.6% as of May 2026 per SDAR data, staging and professional photography help you maximize your price and minimize days on market. For a relocating seller, fewer days on market means less overlap between your old and new home obligations.
Can I manage the sale from out of state if I move before it closes?
You can, but it adds complexity. Remote sellers need to coordinate inspections, repairs, and final walkthroughs through their agent. This is one reason a rent-back or bridge loan often makes more sense: it gives you time to complete the sale while still physically present.
How do I choose the right real estate agent in San Diego for a relocation sale?
Look for an agent with specific relocation experience, strong negotiation skills, and a vetted vendor network for staging, inspections, and repairs. As a top 1% real estate agent in San Diego County and Associate Broker with 18 years of experience, I offer a complimentary attorney review of contracts and disclosures, covered by me even if escrow cancels, which provides an extra layer of protection during a complex relocation transaction.
The Bottom Line
Selling your Clairemont home before relocating out of state in 2026 is not only doable, it’s something the current market actively supports. With inventory under 1.2 months, homes selling in as few as 15 to 17 days, and strong buyer demand across every Clairemont sub-area, you have the leverage to negotiate closing terms that protect you from carrying two mortgages or bouncing between hotels.
The key is choosing the right strategy for your timeline, whether that’s a rent-back, a synchronized closing, a bridge loan, or in rare cases a cash sale, and executing it with precision from day one. If you’re planning a move out of state and want a calm, clear plan for your Clairemont sale, reach out to me, Scott Cheng, at 858-405-0002. I’m here to help you move forward with confidence.