Can You Actually Afford to Buy a Home in Kensington San Diego in 2026
How do I know if I can actually afford to buy a home in Kensington, San Diego in 2026, and what income, credit score, and down payment do I really need right now?
You can buy a condo in Kensington with roughly $20K down and a household income near $155K, or a single-family home with $155K+ down and income closer to $280K to $310K, depending on your credit profile and loan type.
Why Kensington San Diego Affordability Matters Right Now
If you have been browsing homes along Adams Avenue and wondering whether you are even in the right ballpark financially, you are not alone. Kensington is one of San Diego’s most desirable central neighborhoods, and the numbers have shifted meaningfully heading into 2026.
The year-to-date median sale price for a single-family home in Kensington sits at $1,555,000, up 6.3% from the same period last year. Condos and townhomes come in at a median of $660,000, up 13.8% year over year. Meanwhile, mortgage rates hover in the 6.0% to 6.8% range, with Fannie Mae projecting rates could settle near 5.9% by late 2026.
What I tell my clients is simple: a cloudy mind can’t make decisions. So let me give you the clear, specific numbers you need to figure out whether Kensington works for your budget right now, or whether you need a plan to get there.
The Two Paths Into Kensington: Single-Family vs. Condo
Here is the reality that shapes everything. Kensington has two very different entry points, and understanding which one fits your situation is the first real decision you need to make.
Single-Family Homes at $1,555,000
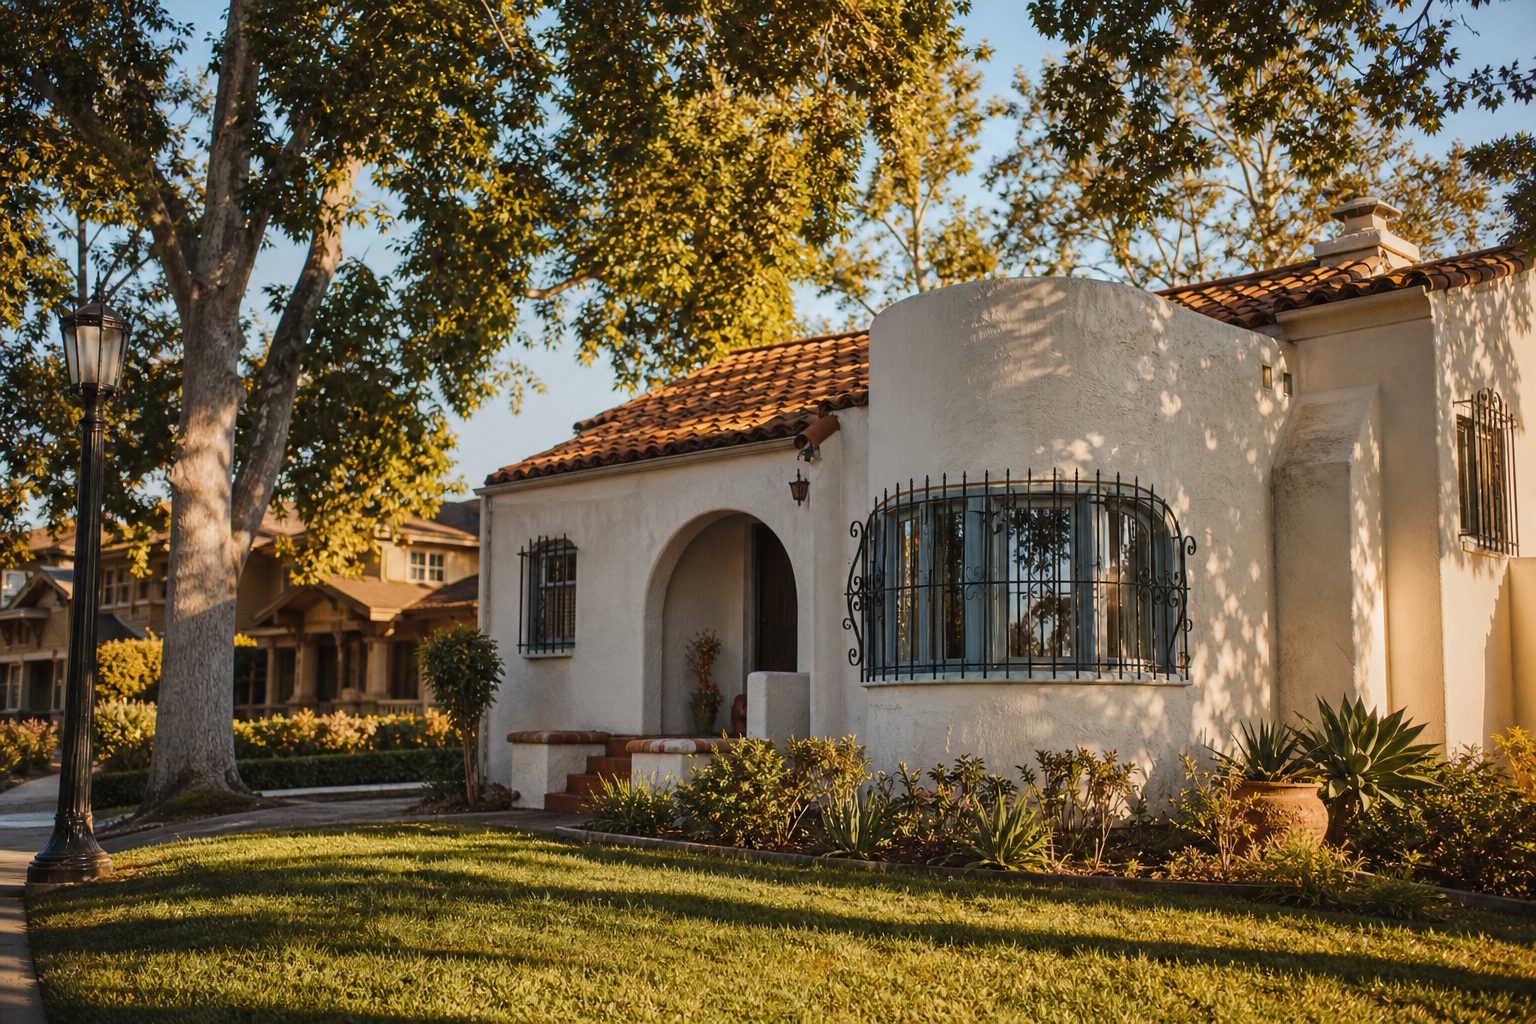
At this price point, you are looking at the preserved Spanish Revival and Craftsman homes from the 1920s and 1930s that give Kensington its distinctive character. These homes sit above the 2026 San Diego County conforming loan limit of $1,104,000, which means you will need a jumbo loan. Jumbo financing comes with stricter credit requirements and larger down payment expectations.
Here is how the numbers break down for a detached home:
- 10% down ($155,500): Loan amount of ~$1,399,500 (jumbo). Estimated monthly payment around $10,800 including taxes and insurance. You would need a household income near $310,000 per year.
- 15% down ($233,250): Monthly payment closer to $10,300. Required income around $295,000.
- 20% down ($311,000): Monthly payment near $9,800. Required income approximately $280,000.
Those income figures assume a 28% front-end debt-to-income ratio, which is the standard most lenders use for the housing portion of your budget.
Condos and Townhomes at $660,000
This is where Kensington becomes genuinely accessible. With a median of $660,000, the condo and townhome market falls well within conforming loan territory, and you have multiple loan options:
- 3% down conventional ($19,800): Monthly payment around $5,400. Required income near $155,000.
- 3.5% down FHA ($23,100): Monthly around $5,600 with mortgage insurance premium. Required income near $160,000.
- 5% down ($33,000): Monthly around $5,300. Required income near $152,000.
- 10% down ($66,000): Monthly around $5,100. Required income near $146,000.
- 20% down ($132,000): Monthly around $4,600. Required income near $132,000.
One couple I worked with recently was eyeing a Spanish Revival single-family home in Kensington and feeling defeated by the price point. Once we ran the numbers on condos in ZIP 92116, they realized they could get into the neighborhood for under $25,000 down. They are now building equity three blocks from Adams Avenue instead of waiting on the sidelines.
What Credit Score Do You Actually Need for Kensington in 2026
Your credit score determines not just whether you qualify, but how much your mortgage actually costs you every month. Here is what lenders in San Diego are looking for right now.
For a Kensington condo (conforming loan):
- FHA minimum: 580 with 3.5% down, or 500 with 10% down
- Conventional minimum: 620
- Competitive rates start at: 720+
- The sweet spot for pricing: 740 and above
For a Kensington single-family home (jumbo loan):
- Minimum: Typically 700 to 720
- Competitive rates: 740+
- Most jumbo lenders also require 6 to 12 months of cash reserves sitting in the bank after closing
So what does a credit score difference actually cost you? On a $640,000 loan at 6.5%, you are paying roughly $4,047 per month in principal and interest. Drop that rate to 6.0% with a stronger credit profile, and your payment falls to about $3,838. That is $209 per month, or $2,508 per year, just from having a higher score. Over 30 years, that adds up to more than $75,000.
If your score is sitting in the low 600s, do not panic. I regularly work with buyers who spend three to six months optimizing their credit before making a move. It is one of the highest-return investments you can make.
How Kensington Compares to Nearby San Diego Neighborhoods
You might be wondering whether Kensington is the right neighborhood for your budget, or whether neighboring areas offer more room. Here is how Kensington stacks up.
In nearby North Park, single-family homes carry a median of $1,232,500, and condos sit at $495,000. That means North Park condos run roughly $165,000 less than Kensington condos, which could translate to meaningfully lower monthly payments.
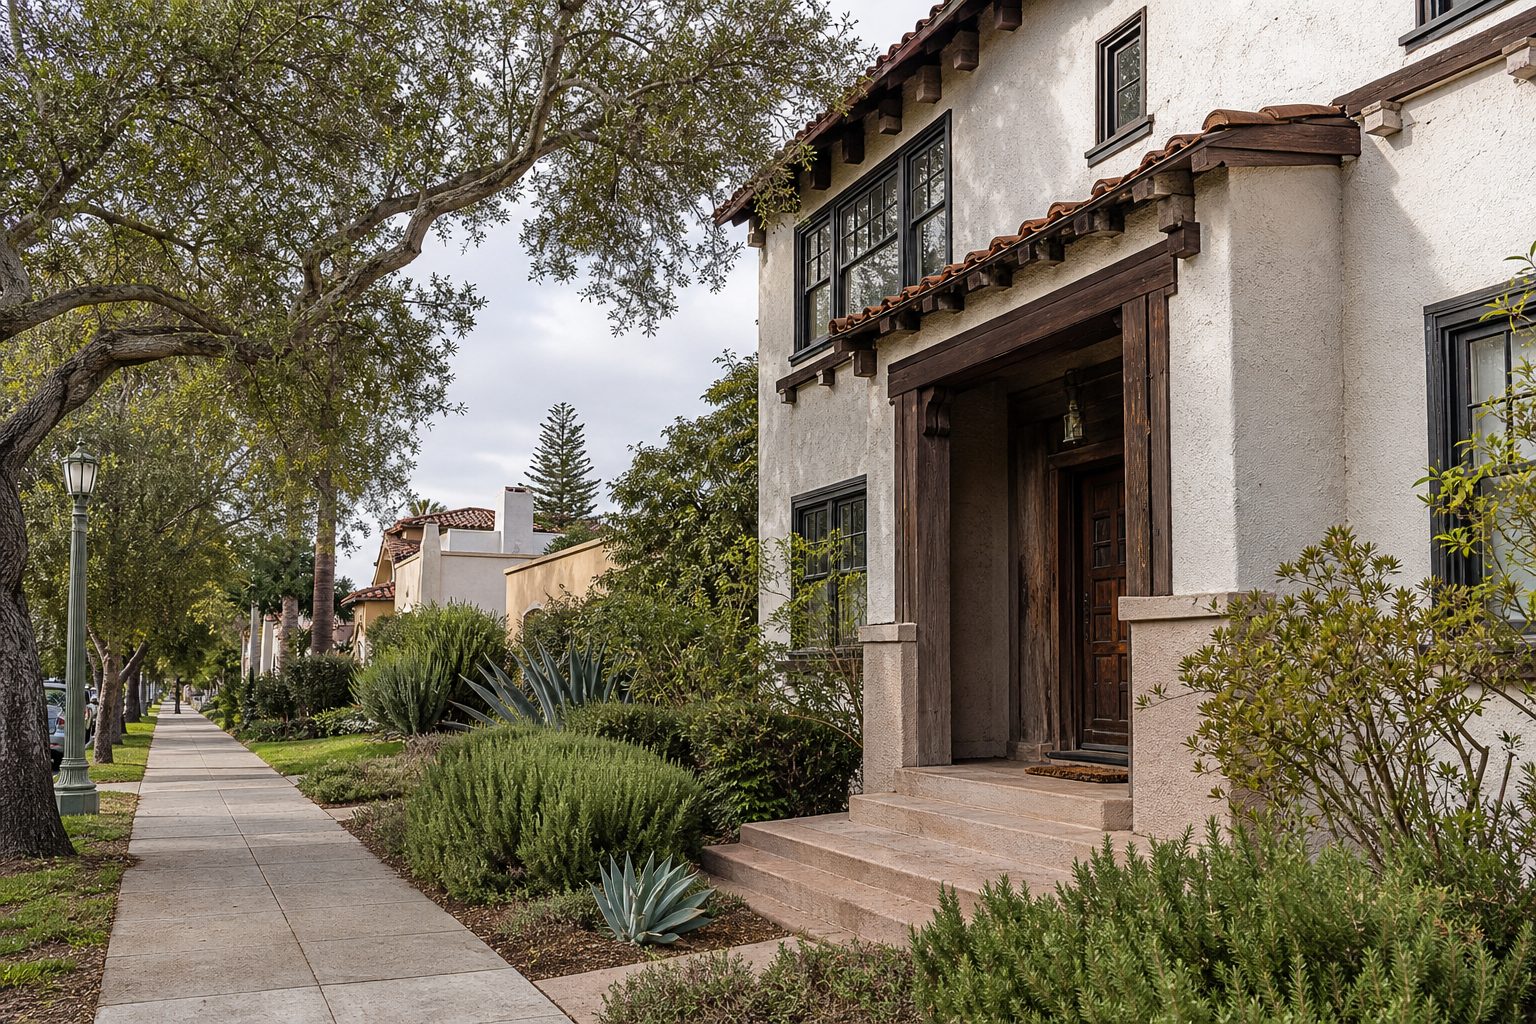
But there is a tradeoff. Kensington’s walkable village feel along Adams Avenue, its classic streetlights, and its architectural cohesion (1920s and 1930s homes that feel curated rather than mixed) create a premium that holds value well. The neighborhood turns over only 10 to 20 listings at any given time across all property types. With 1.8 months of supply for detached homes and just 1.0 months for condos, scarcity is baked into the price.
Having closed over 275 transactions across San Diego County over the past 18 years, I have seen how neighborhoods like Kensington reward buyers who get in early rather than waiting for a dip that rarely materializes. One buyer I worked with purchased a condo near Kensington Elementary a few years back and has already seen meaningful appreciation just from the tight inventory dynamics in this zip code.
Hidden Costs That Affect Whether You Can Afford Kensington
The mortgage payment is only part of the picture. Here is what many buyers overlook when running their Kensington affordability math.
Property taxes: San Diego County property taxes run approximately 1.1% of the purchase price. On a $660,000 condo, that is about $7,260 per year, or $605 per month.
HOA fees: Kensington condos typically carry HOA dues in the $350 to $450 per month range. I always tell buyers to request the HOA budget and reserve study before making an offer. A low HOA with thin reserves can mean a special assessment down the road.
Private mortgage insurance (PMI): If you put less than 20% down on a conventional loan, expect PMI of roughly $100 to $250 per month depending on your credit score and loan amount.
Closing costs: Budget for 2% to 3% of the purchase price. On a $660,000 condo, that means $13,200 to $19,800 on top of your down payment. To prepare for homeownership and understand costs ahead of time, you may want to review resources available from financial authorities. One thing that sets my practice apart is I provide a complimentary attorney review of contracts and disclosures for my buyers, covered by me, even if escrow cancels. That is one less cost you need to worry about.
Maintenance and repairs: Kensington’s homes are charming, but many are 80 to 100 years old. Because I have worked on flips and remodels alongside investors, I can help you understand what a property might cost to maintain and where renovations actually move the needle on value.
The San Diego Mortgage Rate Outlook and What It Means for Kensington Buyers
Where rates land over the next six to twelve months directly affects your purchasing power. The latest projections suggest rates could settle in the low 6s or possibly the high 5s by late 2026. Even a modest drop makes a real difference.
On a $640,000 condo loan, every half-point rate reduction saves you roughly $200 per month. That is meaningful, but here is what I want you to understand: waiting for rates to drop while Kensington inventory remains this tight is a gamble. If rates fall and more buyers jump in, you may face even more competition in a neighborhood that already sells condos at 99.3% of list price within 42 days.
The San Diego median household income is approximately $105,000. Kensington’s entry point requires income above that median, which means you are competing with well-qualified, motivated buyers. Getting pre-approved now puts you in position to move when the right property appears.
Frequently Asked Questions About Buying in Kensington San Diego
What is the minimum down payment to buy a condo in Kensington?
You can purchase a Kensington condo with as little as 3% down on a conventional loan, which is roughly $19,800 on the current median of $660,000. FHA loans allow 3.5% down at $23,100. Keep in mind you will also need funds for closing costs, which typically run 2% to 3% of the purchase price.
What household income do I need for a Kensington single-family home?
Based on the current median of $1,555,000 and a 20% down payment at 6.5% interest, you would need a gross household income of approximately $280,000 per year. With 10% down, that figure jumps to around $310,000 due to the larger loan amount and jumbo financing requirements.
Can I use an FHA loan to buy in Kensington San Diego?
Yes, FHA loans work for Kensington condos priced within the San Diego County FHA limit. You will need a minimum credit score of 580 for the 3.5% down payment option. The condo complex itself must also be FHA-approved, so this is something we verify early in the process.
What credit score do I need for a jumbo loan in San Diego?
Most jumbo lenders require a minimum credit score of 700 to 720. To access competitive interest rates, you will want a score of 740 or above. Jumbo loans also typically require 6 to 12 months of cash reserves after closing, which is more stringent than conventional financing.
How much are property taxes in Kensington?
San Diego County property taxes run approximately 1.1% of the purchase price. For a $660,000 condo, expect roughly $7,260 per year. For a $1,555,000 single-family home, annual property taxes would be approximately $17,100.
Is Kensington a good neighborhood for first-time buyers in 2026?
Kensington can work for first-time buyers, but primarily through the condo market. With condos at a $660,000 median and multiple low-down-payment loan options available, it is accessible for buyers with household incomes in the $132,000 to $160,000 range.
How competitive is the Kensington housing market right now?
Very competitive. Detached homes have only 1.8 months of supply and sell at 95.4% of list price. Condos are even tighter at 1.0 months of supply, selling at 99.3% of list price in an average of 42 days. Buyers have almost no negotiating room on the attached side.
What is the 2026 conforming loan limit for San Diego County?
The 2026 FHFA conforming loan limit for San Diego County is $1,104,000 for a single-family home. Kensington condos fall well within this limit, meaning you get conventional loan pricing. Kensington single-family homes exceed it, pushing you into jumbo territory.
Should I wait for mortgage rates to drop before buying in Kensington?
Fannie Mae projects rates could fall to roughly 5.9% by late 2026. However, lower rates tend to bring more buyers into the market, increasing competition in an already tight neighborhood. With only 10 to 20 active listings at any given time, waiting could cost you more in price appreciation than you save on interest.
How does Kensington compare to North Park for affordability?
North Park condos carry a median of $495,000, roughly $165,000 below Kensington’s $660,000 condo median. Single-family homes in North Park ($1,232,500) are also about $320,000 below Kensington ($1,555,000). North Park offers a more accessible entry point, though Kensington’s tighter inventory often delivers stronger appreciation.
The Bottom Line on Buying in Kensington San Diego
You now have the actual numbers: income requirements, down payment scenarios, credit thresholds, and the hidden costs that shift your total monthly obligation. Kensington is not the most affordable neighborhood in San Diego, but it is one of the most rewarding to own in, with architectural character, walkability along Adams Avenue, and inventory scarcity that protects your investment.
The clearest next step is getting pre-approved so you know exactly where you stand. With 275 five-star reviews and 18 years helping San Diego buyers navigate exactly these decisions, I would welcome the chance to run your specific numbers and build a calm, clear plan. Reach out to me, Scott Cheng, at 858-405-0002 or visit my office at 16516 Bernardo Center Dr. Ste. 300. Let’s figure out what Kensington looks like for your budget.
Have Questions About San Diego Real Estate?
Scott Cheng provides free, no-obligation consultations for buyers, sellers, and investors.
Schedule a Consultation