Down Payment for a Mission Valley San Diego Home in 2026: Your Real Options Compared
How much do I actually need for a down payment to buy a home in Mission Valley, San Diego in 2026, and how do conventional, FHA, and zero-down options compare?
For a typical Mission Valley condo at the year-to-date median of $577,000, per the San Diego Association of REALTORS, you could put down as little as $17,310 (conventional 3%) or $20,195 (FHA 3.5%), and VA-eligible buyers can put zero down.
Why the Down Payment Question Matters in Mission Valley Right Now
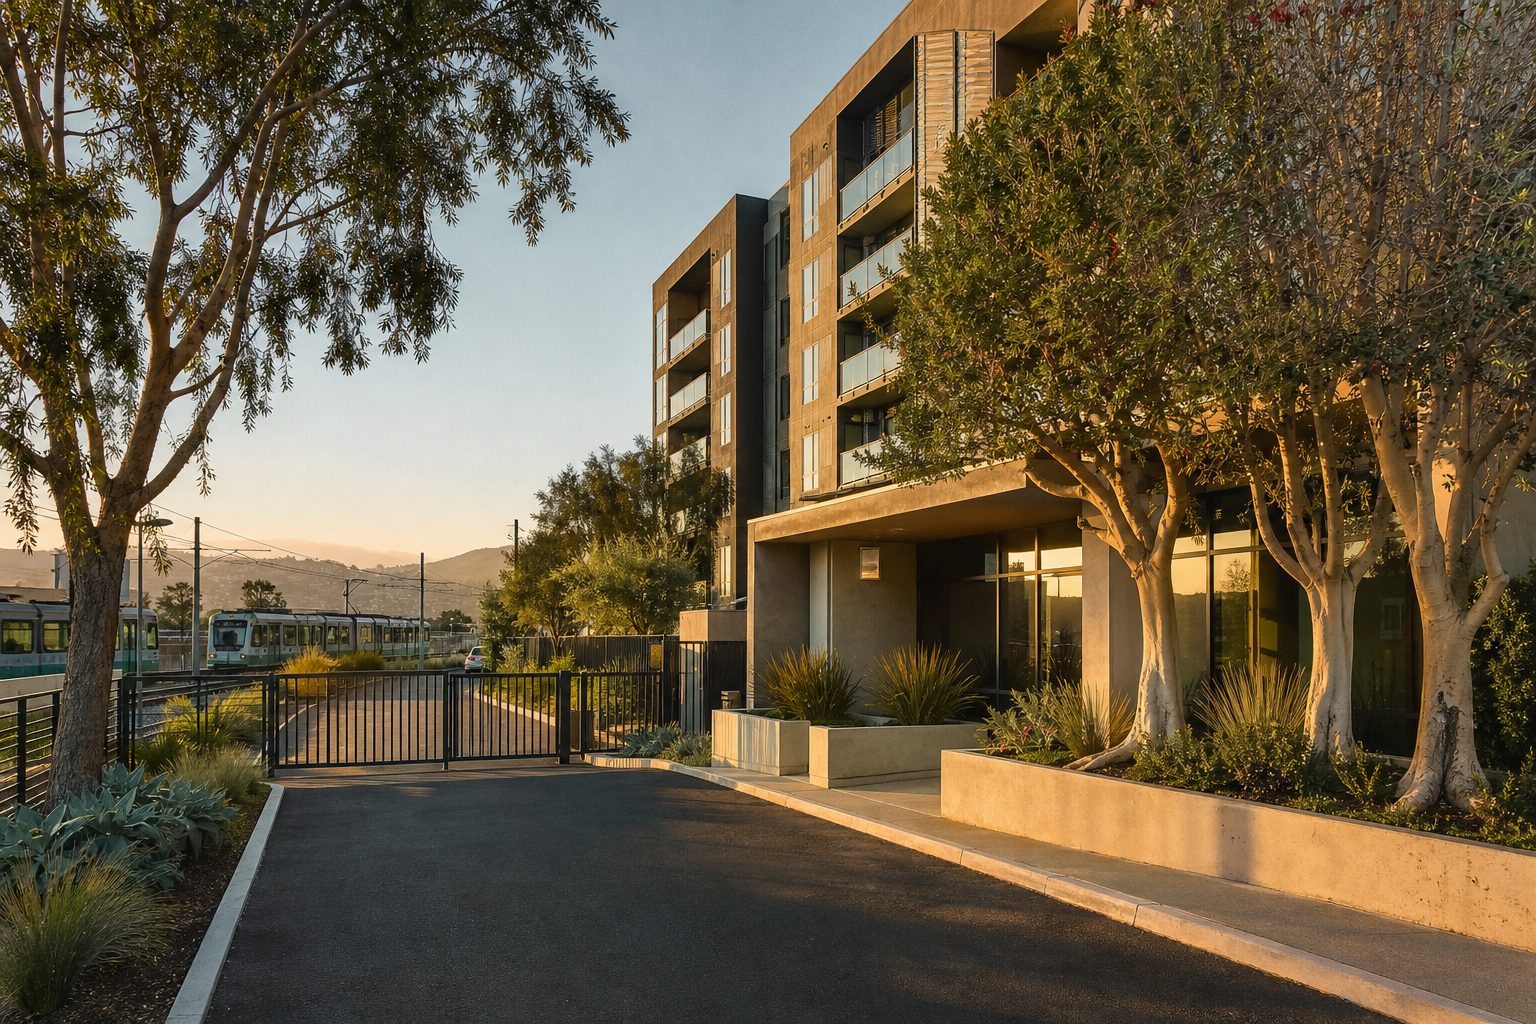
I talk to buyers about this almost every day, and here is the pattern I keep seeing: you know you want to live in Mission Valley because the Green Line trolley, central freeway access, and Snapdragon Stadium area development make it one of San Diego’s most convenient neighborhoods. But you are stuck on the number. How much cash do you actually need to bring to the table?
The good news for 2026 is that Mission Valley’s condo market sits in balanced territory, with 3.6 months of inventory and units selling at 96.2% of original list price, according to the San Diego Association of REALTORS year-to-date data through February 2026. That means you have room to negotiate, and in many cases sellers are open to credits and concessions that offset your closing costs. Countywide, mortgage rates are in the 6.0% to 6.8% range for a 30-year fixed, per the Freddie Mac Primary Mortgage Market Survey, with Fannie Mae forecasting 5.9% by year-end 2026.
So the market conditions are giving you breathing room. Now let’s talk about the actual dollars.
What Mission Valley Homes Actually Cost in San Diego
Before you can figure out your down payment, you need realistic price expectations. Mission Valley is predominantly a condo and townhome market. Detached single-family homes here are rare, with only three closed transactions year-to-date as of early 2026, per SDAR.
Here is what the landscape looks like, based on San Diego MLS data:
- One-bedroom condos typically start in the mid-to-high $400,000s
- Two-bedroom condos range from the mid-$500,000s to mid-$700,000s depending on the community
- Three-bedroom condos and townhomes can range from $670,000 to over $1,200,000 for luxury and resort-style communities
- The year-to-date condo/townhome median is $577,000, down 9.1% from the same period last year, per the San Diego Association of REALTORS
Recent September 2026 transactions in Mission Valley ranged from $345,000 for a one-bed, 530-square-foot unit all the way up to $1,285,000 for a three-bed, four-bath townhome, according to Estately sold data. That’s a wide range, which is actually helpful. It means you have entry points at multiple budget levels.
With 18 years of experience and over 275 closed transactions across San Diego County, I can tell you that Mission Valley consistently offers one of the more accessible entry points in central San Diego. For context, North Park’s median condo price is $555,000 as of October 2026 per San Diego MLS, but with only 1.7 months of inventory, competition there is tighter. Mission Valley’s extra supply gives you leverage.
Conventional Loan Down Payment for Mission Valley Buyers
A conventional loan is the most common option, and it is more flexible than many first-time buyers realize.
Minimum Down Payment Options
- 3% down if you are a first-time buyer using Fannie Mae HomeReady or Freddie Mac Home Possible programs
- 5% down for repeat buyers
- 20% down to avoid private mortgage insurance (PMI) entirely
What That Looks Like in Real Dollars
Here is the math at Mission Valley’s key price points:
- $450,000 one-bedroom condo: 3% down is $13,500. At 5% it is $22,500. At 20% it is $90,000.
- $577,000 median condo: 3% down is $17,310. At 5% it is $28,850. At 20% it is $115,400.
- $750,000 upper-range two-bedroom: 3% down is $22,500. At 5% it is $37,500. At 20% it is $150,000.
What I tell my clients: if you put down less than 20%, expect PMI to add roughly $200 to $500 or more per month depending on your loan size and credit score. That cost is real, but it does not have to be a dealbreaker. PMI drops off once you reach 20% equity, and you can start building that equity from day one.
San Diego County is classified as a high-cost area. The 2025 conforming loan limit was $1,006,250 for a single-unit property, per the FHFA, and the 2026 limit is expected to be similar or slightly higher. That means virtually every Mission Valley condo falls well within conforming loan territory, which keeps your rate competitive.
FHA Loan Down Payment for Mission Valley in 2026
If your credit score is solid but your savings are still growing, FHA financing can be a strong path.
The Basics
- 3.5% down with a credit score of 580 or higher
- 10% down with a credit score between 500 and 579
- Upfront mortgage insurance premium (UFMIP): 1.75% of the loan amount, which can be rolled into the loan
- Annual MIP: 0.55% of the loan amount for the life of the loan if you put less than 10% down
Real Numbers at Mission Valley Prices
- $450,000 condo: 3.5% down is $15,750. The UFMIP of roughly $7,598 can be financed into the loan. Total cash needed including estimated closing costs of 2% to 3% is approximately $18,000 to $22,000.
- $577,000 median condo: 3.5% down is $20,195. Total cash needed including closing costs is approximately $23,000 to $28,000.
- $750,000 upper-range unit: 3.5% down is $26,250. Total cash needed is approximately $29,000 to $35,000.
The 2025 FHA loan limit for San Diego County was $1,006,250, per HUD, matching the conforming limit ceiling. So FHA covers the full range of Mission Valley pricing.
One Critical Catch for Mission Valley FHA Buyers
Not all Mission Valley condo complexes are FHA-approved. This is a detail that trips up buyers constantly. Before you fall in love with a unit, your lender needs to verify that the specific community appears on the FHA-approved condo list through HUD. Having closed over 275 transactions across San Diego, I’ve seen this issue derail timelines more than once. I always recommend checking approval status early, before you even write an offer.
Zero-Down and Low-Down Payment Programs for San Diego Buyers
Can you buy in Mission Valley with nothing down? In certain situations, yes.
VA Loans: Zero Down, No Monthly Mortgage Insurance
If you are an eligible veteran, active-duty service member, or surviving spouse, a VA loan is one of the most powerful tools available. San Diego is a major military hub, with Naval Base San Diego, Marine Corps Air Station Miramar, and Camp Pendleton nearby.
- No down payment required, even on higher-priced homes
- No PMI or MIP, which saves you hundreds per month compared to FHA or conventional with less than 20% down
- VA funding fee of 1.4% to 3.6% applies and can be financed into the loan, but it is waived for disabled veterans
On a $577,000 Mission Valley condo, a VA buyer could potentially walk in with just closing costs and reserves. That’s a meaningful difference compared to needing $17,000 to $20,000 or more for a conventional or FHA down payment.
USDA Loans: Not Available in Mission Valley
USDA loans offer zero down, but Mission Valley is an urban area that does not qualify, per the USDA eligibility map. This option is off the table here.
California Down Payment Assistance Programs
Several state and local programs can reduce or cover your out-of-pocket costs:
- CalHFA MyHome Assistance Program: A deferred-payment junior loan of up to 3.5% of purchase price for down payment and closing costs
- CalHFA Zero Interest Program (ZIP): Up to 3% of the first mortgage amount as a zero-interest deferred loan for closing costs
- CalHFA Forgivable Equity Builder Loan: Up to 10% of the purchase price as a forgivable loan after five years of occupancy
- San Diego Housing Commission (SDHC) offers additional down payment and closing cost assistance to first-time buyers, though income limits and purchase price limits apply, and funding availability varies by cycle
- National Homebuyers Fund (NHF): Offers up to 5% of the loan amount as a grant that does not need to be repaid, compatible with FHA, VA, and conventional loans
Income limits apply to most of these programs, typically capped around 150% of area median income. With San Diego’s median household income at $104,321, according to Census data, many Mission Valley buyers fall within eligibility ranges.
How to Choose the Right Down Payment Path for Mission Valley
Here is the framework I walk my buyers through. A cloudy mind can’t make decisions, so let’s simplify this.
Start with These Three Questions
- Are you VA-eligible? If yes, that is almost always your strongest option. Zero down plus no monthly mortgage insurance is hard to beat.
- Is your target condo FHA-approved? If you are leaning FHA, verify this first. It narrows your choices but can still be a solid path, especially with CalHFA assistance layered on top.
- What is your credit score and savings timeline? Conventional at 3% down with strong credit may cost less over the life of the loan than FHA, because PMI can be removed while FHA’s MIP cannot (at less than 10% down).
Rated 5 out of 5 stars across 275 client reviews, I’ve guided buyers through every one of these scenarios across San Diego County. One extra layer of protection I provide: a complimentary attorney review of contracts and disclosures, covered by me, even if escrow cancels. When you are navigating loan types, down payment assistance programs, and negotiation strategy all at once, that kind of support matters.
Frequently Asked Questions About Mission Valley Down Payments in 2026
What is the minimum down payment for a Mission Valley condo with a conventional loan?
First-time buyers can put as little as 3% down using programs like Fannie Mae HomeReady or Freddie Mac Home Possible. On the year-to-date Mission Valley condo median of $577,000, per the San Diego Association of REALTORS, that comes to $17,310. Repeat buyers typically need at least 5%.
How much do I need for an FHA down payment on a $577,000 Mission Valley condo?
With a credit score of 580 or higher, FHA requires 3.5% down, which is $20,195 on a $577,000 purchase. Add estimated closing costs of 2% to 3% of the purchase price, and total cash needed is approximately $23,000 to $28,000.
Can I buy a home in Mission Valley with zero down payment?
Yes, if you are eligible for a VA loan. VA loans require no down payment and carry no monthly mortgage insurance. USDA loans, another zero-down option, are not available in Mission Valley because it is classified as an urban area per the USDA eligibility map.
Are all Mission Valley condos eligible for FHA financing?
No. FHA requires the specific condo community to be on the HUD-approved condo list. Not all Mission Valley complexes have this approval. You should verify eligibility with your lender early in the search process, before submitting an offer.
What is the difference in monthly cost between 3% down and 20% down in Mission Valley?
On a $577,000 condo, putting 3% down means financing roughly $559,690 plus PMI, while 20% down means financing $461,600 with no PMI. The difference in monthly principal and interest, combined with PMI savings, can range from $600 to $900 per month depending on your rate and credit score.
What San Diego down payment assistance programs can I use in Mission Valley?
CalHFA offers the MyHome Assistance Program (up to 3.5% deferred loan), the Zero Interest Program (up to 3% for closing costs), and the Forgivable Equity Builder Loan (up to 10% forgivable after five years). The San Diego Housing Commission and National Homebuyers Fund also offer grants and deferred loans. Income limits apply.
Is Mission Valley a buyer’s market or seller’s market in 2026?
The condo segment in Mission Valley sits in balanced territory with 3.6 months of inventory and units selling at 96.2% of original list price, per the San Diego Association of REALTORS year-to-date data through February 2026. That gives you negotiating room that is harder to find in tighter San Diego neighborhoods.
How much are closing costs on top of the down payment in Mission Valley?
Closing costs in San Diego typically run 2% to 3% of the purchase price. On a $577,000 condo, expect roughly $11,500 to $17,300 in closing costs covering lender fees, title insurance, escrow, and prepaid items. In this market, you may be able to negotiate seller credits to offset some of these costs.
Should I wait for lower rates before buying in Mission Valley?
Rates are in the 6.0% to 6.8% range as of 2026, per the Freddie Mac Primary Mortgage Market Survey, with Fannie Mae forecasting 5.9% by year-end 2026. If rates drop meaningfully, pent-up demand tends to flood back, increasing competition and pushing prices higher. Buying now with the option to refinance later is a strategy worth serious consideration.
Does PMI go away on a conventional loan for a Mission Valley condo?
Yes. On a conventional loan, PMI can be removed once you reach 20% equity in the property, either through paying down the balance or through appreciation. FHA’s mortgage insurance premium, by contrast, stays for the life of the loan if you put less than 10% down. This is a significant long-term cost difference.
The Bottom Line on Buying in Mission Valley, San Diego
You do not need $100,000 in the bank to buy a home in Mission Valley. With conventional loans starting at 3% down, FHA at 3.5%, VA at zero, and multiple California assistance programs that can cover part or all of your down payment and closing costs, the real question is which path fits your financial picture.
Mission Valley’s balanced condo market, central location along the Green Line trolley, and proximity to Snapdragon Stadium’s ongoing development make it a neighborhood where convenience and long-term value line up. If you are ready to talk through your specific numbers and figure out the smartest path to homeownership here, reach out to me directly at 858-405-0002 or visit my office at 16516 Bernardo Center Dr. Ste. 300. I’m Scott Cheng with REAL Brokerage, and I’d welcome the chance to bring you clean information and a calm plan you can feel good about.
Have Questions About San Diego Real Estate?
Scott Cheng provides free, no-obligation consultations for buyers, sellers, and investors.
Schedule a Consultation