Is Buying in Banker’s Hill San Diego a Smart Move in 2026?
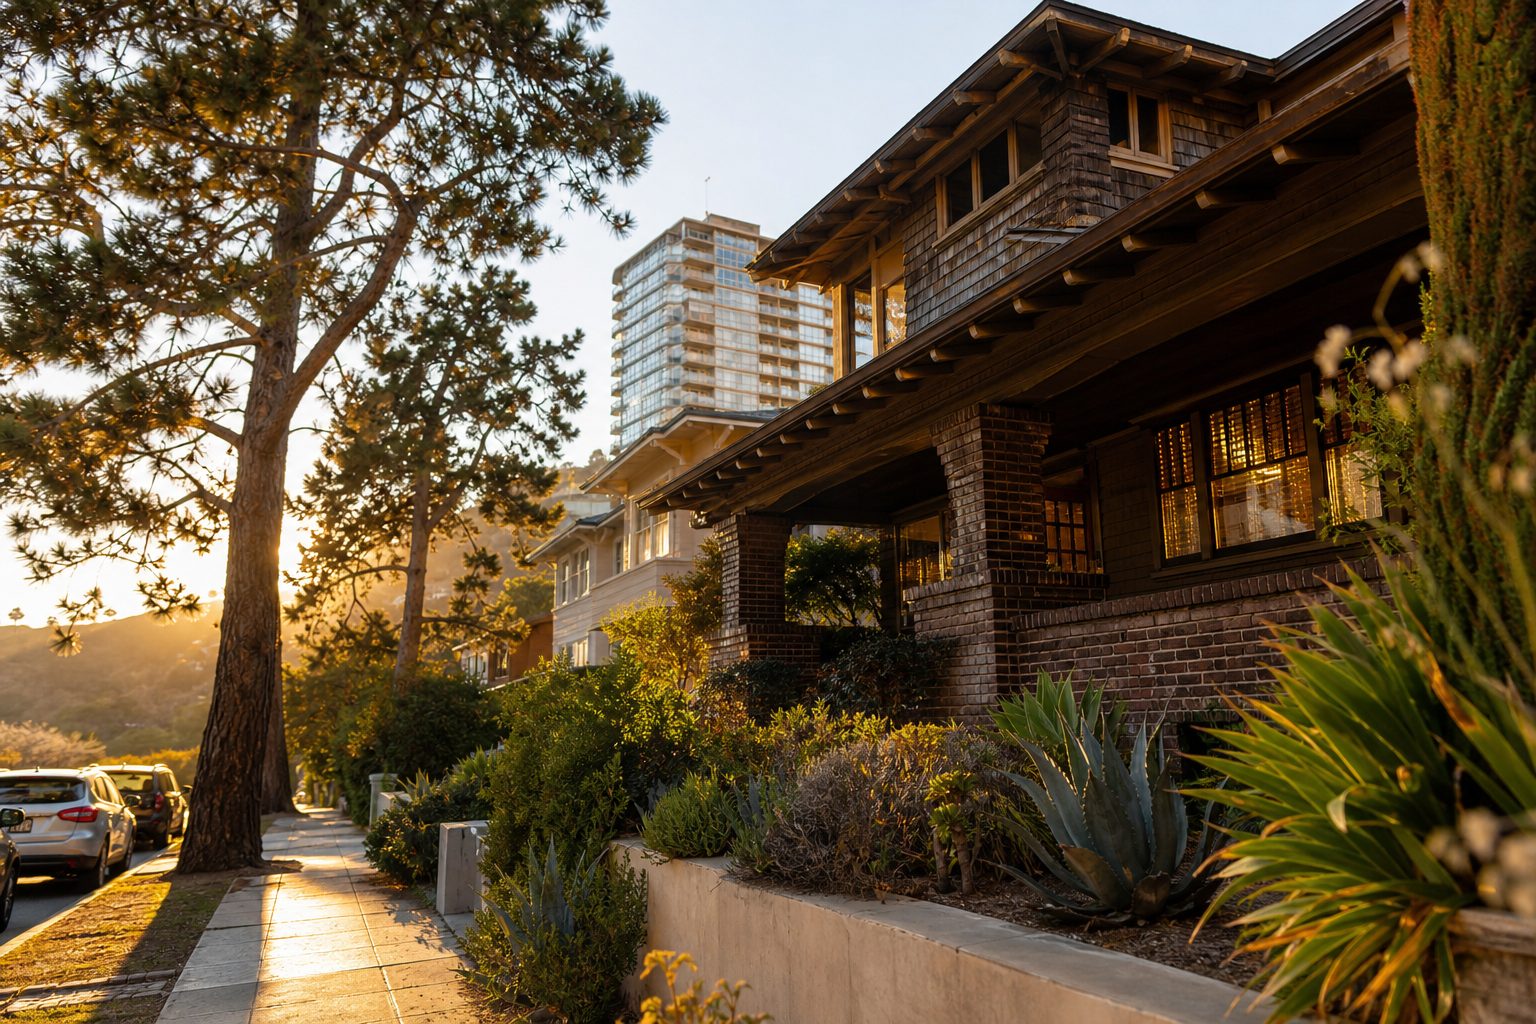
If you’re thinking about buying a home in Banker’s Hill, San Diego, should the wave of high-density development projects worry you, or does the construction pipeline actually signal long-term strength for the neighborhood?
Banker’s Hill can still be a smart buy in 2026, but only if you choose the right building, underwrite the HOA carefully, and understand that the condo segment and the detached segment are on two very different tracks right now.
Why This Matters Right Now for Banker’s Hill Buyers
You’re asking this question at the right time. Banker’s Hill has 9 apartment projects under construction as of 2026, with close to 1,600 new units expected by 2028, according to development tracking data. That is a massive influx for a neighborhood this compact.
At the same time, the San Diego housing market has split into two tracks in 2026. Detached homes are holding their value, while older condos slip under HOA pressure, per multiple local market analysts. Rising HOA dues, SB 326 inspection costs, and higher insurance are the main drag on condo values.
So if you’re looking at Banker’s Hill, you need to understand exactly which side of that divide your target property falls on. A cloudy mind can’t make decisions, and this is one of those situations where the details change everything. With 18 years helping San Diego buyers navigate shifting markets, I can tell you that the answer is not a simple yes or no. It depends on what you’re buying, what you’re paying for HOA, and how long you plan to hold.
The Banker’s Hill San Diego Development Pipeline: What’s Actually Being Built
Let me walk you through what’s happening on the ground, because the scope of construction is genuinely significant.
Major projects currently in various stages:
- The Broderick (formerly Quince): A 17-story, 260-unit residential tower at Fourth Avenue and Spruce Street, with retail space, developed by CAST Communities. Completion targeted for 2026.
- Park Summit: A 21-story mixed-use building with 265 apartments and extended-stay units, with completion slated for late 2026.
- The Park, Bankers Hill: A 14-story project featuring 60 luxury condominiums plus townhomes, with commercial space and underground parking.
- Interwest Capital Project: A 12-story, 129-unit apartment community with a mix of studios, one-bedrooms, and two-bedrooms.
- Foley Development Complex: A 56-unit apartment project at a total cost of $63 million, including ground-floor retail and a medical office building.
Here’s what I want you to notice. Most of these are rental apartment projects, not condominiums for sale. That distinction matters enormously for your resale value question. New rental supply and new for-sale supply affect the market differently.
City officials have noted that projects approved under Complete Communities will be judged by how well they connect residents to transit, green space, and neighborhood services. For Banker’s Hill, that debate is literally built into the skyline now.
How High-Density Development Could Affect Your Banker’s Hill Resale Value
This is the heart of your concern, so let me be direct.
The Risk Side
The downtown and urban San Diego condo market is already soft. In the 92101 ZIP code (which neighbors Banker’s Hill), the median condo price is hovering near $795,000, inventory has climbed to roughly 7 months of supply, and condos are taking 70 to 90 or more days to sell, according to mid-2026 market data. The months supply of inventory came in at 9.40 months in that submarket, clearly buyer’s market territory.
When you add close to 1,600 new units to a neighborhood that is already seeing longer days on market for attached properties, the math creates near-term pricing pressure for existing condo owners. That is real.
The Strength Side
San Diego does not have enough homes overall. The coast, the canyons, and limited land mean builders cannot add supply quickly at the macro level. Countywide, the median home price reached $1,085,000 in June 2026, a 5.9% increase from the prior year, per California Association of Realtors data.
Banker’s Hill also holds irreplaceable location advantages. The neighborhood sits two blocks from Balboa Park, is walkable to the San Diego Zoo, Little Italy, Downtown, and Hillcrest, and offers canyon and ocean views that new construction in other areas simply cannot replicate.
What I tell my clients is this: new construction brings growing pains in the short term, but neighborhoods that attract this level of developer investment tend to appreciate over a full market cycle. The question is whether you can ride through two to four years of absorption.
The Two-Track San Diego Condo Market and What It Means in Banker’s Hill
You need to understand the countywide pattern, because it directly shapes your Banker’s Hill decision.
The San Diego housing market in 2026 is running on two very different tracks. Detached single-family homes have held near their 2022 peak. Older condos and townhomes, meanwhile, are down about 10% to 15%, per local analyst reporting. The median price for attached homes countywide declined 1.1% to $670,000, as increased inventory and broader selection gave buyers more negotiating room, according to June 2026 data.
Why the split? Rising HOA dues, SB 326 inspection costs, and higher insurance are the main forces pushing condo values down. Older buildings that haven’t completed their reserve studies or addressed deferred maintenance are being punished hardest by both buyers and lenders.
So if you’re buying a newer condo or townhome in Banker’s Hill with a well-funded HOA and completed SB 326 compliance, you’re in a very different position than someone purchasing in an older building with a looming special assessment. Having closed over 275 transactions in San Diego, I can tell you that the building’s financial health matters just as much as the unit itself.
What Smart Banker’s Hill Buyers Are Doing Differently in 2026
The market is giving you leverage you have not had in years. Here’s how to use it.
Negotiate from strength. Buyers are routinely receiving concessions of 1% to 3%, and longer market times are now common in the attached segment. For buyers, that means real negotiating room for the first time in years. You should ask for credits toward closing costs, rate buydowns, or repairs.
Underwrite the building, not just the unit. This is something I emphasize with every condo buyer. Get the HOA financials, the reserve study, and any SB 326 inspection reports before you fall in love with the view. HOA health can make or break long-term value.
Get pre-approved and confirm warrantability early. The 2026 conforming loan limit for San Diego County is $1,104,000 per FHFA data, the highest on record, which means many Banker’s Hill condos can still be financed with conforming rather than jumbo terms. But non-warrantable projects create financing headaches that derail offers.
Consider the hold period. If you’re planning to own for seven or more years, the current development pipeline is much less concerning. The new units will be absorbed, the neighborhood infrastructure will mature, and the walkability premium that Banker’s Hill already commands will only strengthen. If you’re thinking two to three years, the near-term supply overhang is a real risk to your equity.
Rates are currently running in the low-6% range, per spring 2026 data, and Fannie Mae projects the average 30-year fixed rate will fall to roughly 5.9% by year end. That trajectory is favorable for your purchasing power over the coming months.
How Banker’s Hill Compares to Other San Diego Neighborhoods for Buyers
Context matters. When evaluating Banker’s Hill, you should understand how nearby neighborhoods are performing.
- North Park has a 2026 median sale price of $1,232,500 for single-family homes and $495,000 for condos, per recent sales data. It offers a Walk Score of 86 and a thriving restaurant and brewery scene along 30th Street.
- Mission Hills is significantly pricier, with an average house price around $1.66M, up 19.7% year over year according to competitive market data. Bungalows and condos there start in the $900K to $1.5M range.
- Downtown (92101) is where the condo softness is most pronounced, with the average price per square foot at $738 and homes selling at an average of 97.19% of asking price.
Banker’s Hill sits between these markets geographically and, in many ways, in terms of price positioning. Its proximity to Balboa Park and its mix of historic character and new development give it a different flavor than any of its neighbors.
Frequently Asked Questions About Buying in Banker’s Hill San Diego
Is Banker’s Hill a buyer’s market or seller’s market in 2026?
For condos and attached properties in the greater downtown and urban San Diego area, you’re looking at buyer’s market conditions. Inventory in the 92101 ZIP code has climbed to roughly 7 to 9 months of supply as of mid-2026. Detached homes in San Diego County, by contrast, remain competitive at about 18 days median time on market, per June 2026 data.
Will the 1,600 new units in Banker’s Hill crash condo prices?
Not likely a crash, but near-term pressure is real. Most of the new units are rental apartments, not for-sale condos. However, rental supply does compete with condo ownership appeal, especially for younger buyers. Expect two to four years of absorption before the market fully digests this inventory.
How are HOA costs affecting Banker’s Hill condo values?
Rising HOA dues, SB 326 inspection costs, and higher insurance are the main drag on condo values across San Diego’s urban core. Older buildings with deferred maintenance or underfunded reserves are being discounted most aggressively by both buyers and lenders.
What is the conforming loan limit for Banker’s Hill properties in 2026?
The 2026 FHFA conforming loan limit for San Diego County is $1,104,000 for a single-family or single-unit property. This is the highest on record and means many Banker’s Hill condos qualify for conforming financing rather than jumbo terms.
Should I buy a new-construction condo or an older unit in Banker’s Hill?
Newer construction with well-funded HOAs and completed SB 326 compliance is generally a safer bet for holding resale value. Older buildings face more uncertainty around future assessments. Evaluate the reserve study and building financials carefully before committing.
How long should I plan to hold a Banker’s Hill condo to protect my investment?
A seven-year or longer hold gives you the strongest cushion against near-term supply pressure. With close to 1,600 new units arriving by 2028, the first few years may see flat or slightly negative price movement for existing condos.
What concessions can I negotiate as a Banker’s Hill buyer right now?
Buyers are commonly receiving 1% to 3% in concessions as of 2026. You can negotiate credits toward closing costs, interest rate buydowns, or repair items. This is the most leverage buyers have had in the urban San Diego market in years.
Is Banker’s Hill walkable enough to justify condo living?
The neighborhood sits two blocks from Balboa Park, is walkable to the San Diego Zoo, Little Italy, Downtown, and Hillcrest. Projects like The Broderick sit atop the highest point of Banker’s Hill with canyon and ocean views. The walkability and location premium here is genuine and difficult to replicate elsewhere.
What mortgage rates should I expect when buying in Banker’s Hill?
Rates are running in the low-6% range as of spring 2026. Fannie Mae projects the average 30-year fixed rate will fall to roughly 5.9% by year-end 2026. That gradual decline improves your purchasing power over the coming months.
How do I know if a Banker’s Hill condo building is warrantable?
Ask your lender to verify warrantability early in the process. Non-warrantable buildings, often those with high investor-ownership ratios or litigation, limit your financing options and can reduce your future buyer pool. Confirming this upfront prevents costly surprises.
The Bottom Line on Buying in Banker’s Hill San Diego in 2026
Banker’s Hill is not a blanket yes or blanket no in 2026. It’s a nuanced decision that depends on the specific property, the building’s financial health, and your timeline.
If you choose a well-maintained or newly built unit with a funded HOA, plan to hold for seven or more years, and negotiate from the buyer leverage this market is offering, Banker’s Hill’s irreplaceable location next to Balboa Park and its walkable urban lifestyle can reward you over a full market cycle.
If you’re looking for a short-term hold or considering an older building with unclear HOA health, the development pipeline and condo market headwinds create real risk.
Before you make a final decision about purchasing, consider learning more about down payment assistance programs available for first-time buyers, which can strengthen your financial position regardless of the neighborhood.
With 275 five-star reviews and 18 years of helping San Diego buyers navigate exactly these kinds of decisions, I’m happy to walk through the numbers on any specific Banker’s Hill property you’re considering. You can reach me, Scott Cheng, at 858-405-0002 or through my team at Scott Cheng San Diego Realtor. I offer a complimentary attorney contract review with every transaction, covered by me, even if escrow cancels. Let’s make sure you have a calm, clear plan before you move forward.
Have Questions About San Diego Real Estate?
Scott Cheng provides free, no-obligation consultations for buyers, sellers, and investors.
Schedule a Consultation