True Carrying Costs of Owning a Luxury Home in La Jolla in 2026
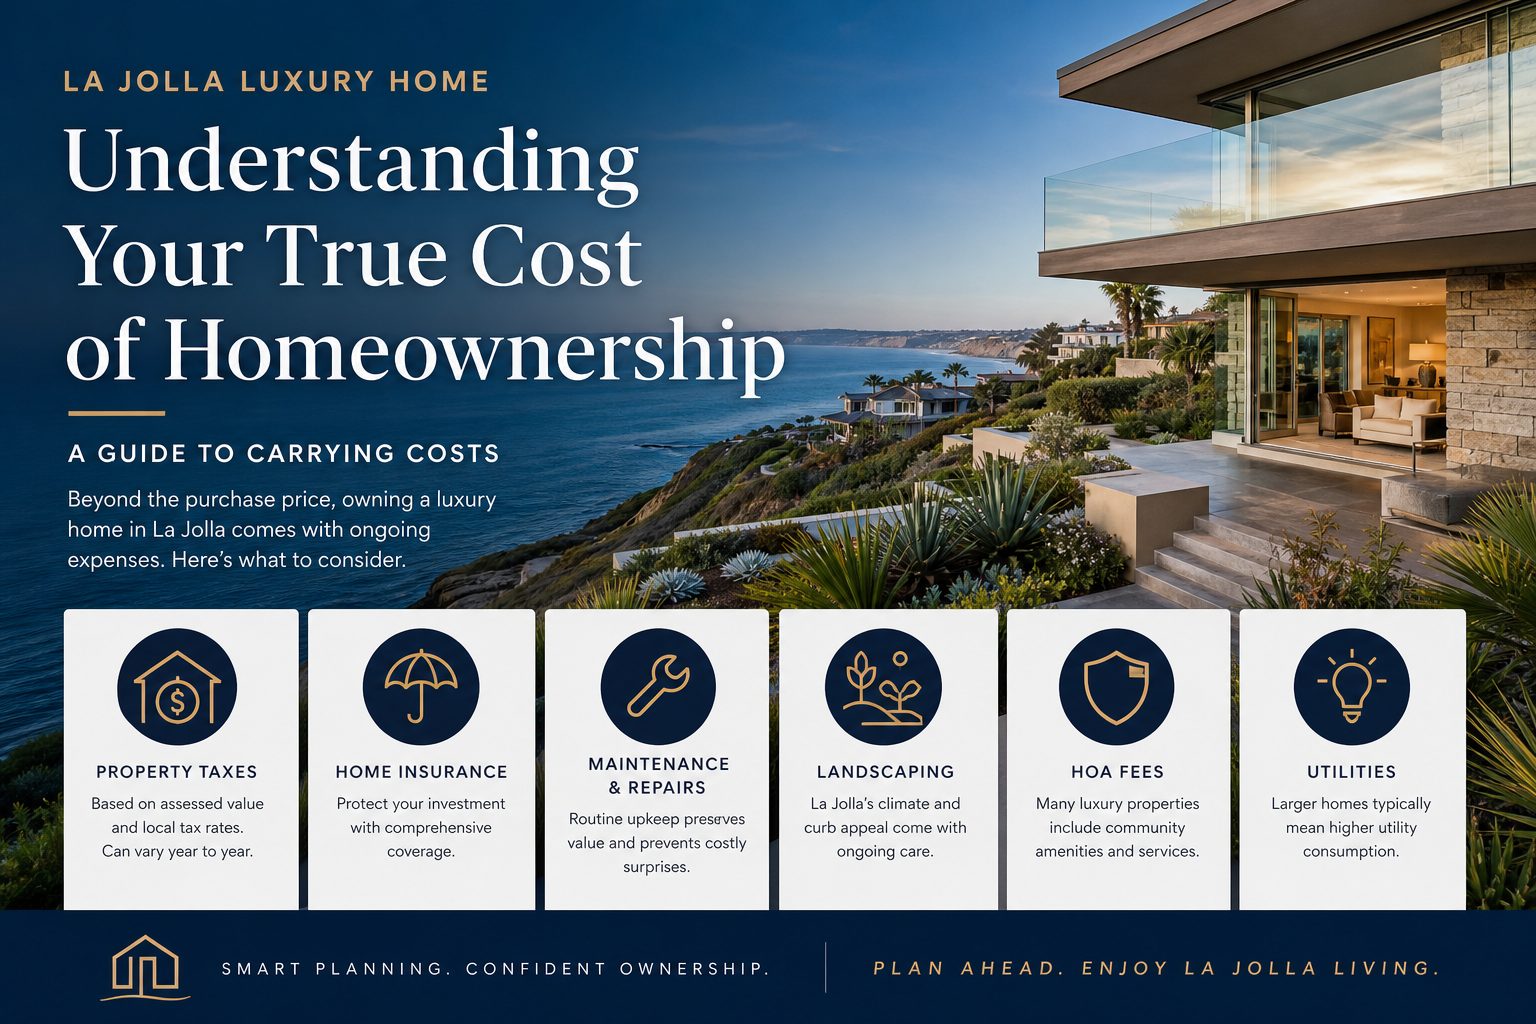
What are the true all-in carrying costs of owning a luxury home in La Jolla, San Diego, in 2026 beyond the mortgage, including property taxes, HOA, insurance, and maintenance on a $3 million to $5 million estate?
For a $3M to $5M La Jolla estate, expect $90,000 to $200,000 or more per year in carrying costs beyond your mortgage, covering property taxes, insurance, HOA (if applicable), and maintenance.
Why This Matters Right Now in San Diego
These numbers surprise people. I’ve had more than a few conversations this year with buyers who built a beautiful budget around a mortgage payment, only to realize the “other stuff” adds up to a second mortgage.
And here’s what makes 2026 particularly important. With another round of tech layoffs circulating through San Diego, particularly affecting Qualcomm engineers who purchased La Jolla properties during the boom years, some luxury homeowners are reassessing whether they can sustain these carrying costs long term. A cloudy mind can’t make decisions, so let me lay out every number clearly.
San Diego County property values reached a record $845 billion as of January 2026, the 14th consecutive year of increases. That 4.86% jump is generating roughly $8.1 billion in property tax revenue. Whether you’re buying into this market or holding an existing estate, understanding the full picture is essential.
Property Taxes on a La Jolla Estate: The Largest Annual Line Item
Your property tax bill will be the single biggest carrying cost beyond the mortgage. In La Jolla, the effective rate runs approximately 1.20% to 1.25% of your assessed (purchase) value.
Here’s what that looks like at different price points:
- $3,000,000 purchase at 1.20% effective rate: approximately $36,000 per year
- $4,000,000 purchase at 1.20% effective rate: approximately $48,000 per year
- $5,000,000 purchase at 1.20% effective rate: approximately $60,000 per year
One thing I always clarify for clients: thanks to Proposition 13, your assessed value can only increase by a maximum of 2% annually, regardless of market appreciation. So your tax bill in year five will be notably lower than what a new buyer would pay at that point.
What does this mean for your actual budget? At the $4M mark, you’re looking at $4,000 per month in property taxes alone before you factor in anything else.
The SALT Deduction Reality Check
For 2026, the state and local tax (SALT) deduction is capped at $40,400 for most filers. If you’re paying $48,000 in property taxes on a $4M home and you also owe California state income tax, you will almost certainly exceed the cap. That means a significant portion of your property tax provides zero federal deduction. Factor this into your true after-tax carrying cost.
A La Jolla Perk: No Mello-Roos
One genuine advantage of buying in an established community like La Jolla versus newer master-planned suburbs further inland is the absence of heavy Mello-Roos special taxes. In communities like 4S Ranch or Del Sur, those fees can add thousands to your annual bill. Some La Jolla neighborhoods like Bird Rock do carry small Maintenance Assessment District fees for local landscaping, but these are minor in comparison.
HOA Fees in La Jolla: It Depends Entirely on Property Type
HOA costs in La Jolla range from zero to staggering, depending on what you buy. Having closed over 275 transactions across San Diego, I can tell you that this is the line item where I see the widest variation.
- Single-family estates in neighborhoods like La Jolla Farms, Muirlands, or La Jolla Shores: typically $0 to $200 per month (no formal HOA or very minimal)
- Gated luxury communities: $300 to $800 per month, covering gates, common landscaping, and shared amenities
- Luxury oceanfront condos: $1,200 to $2,500+ per month, especially in older buildings with elevators, pools, and concierge services
Here’s a scenario that comes up regularly. A couple relocating from the East Coast fell in love with an oceanfront condo in La Jolla priced at $3.8M. Beautiful unit. But the HOA was $2,100 per month, and a pending SB 326 balcony inspection had triggered talk of a special assessment. When we mapped out total carrying costs, the annual HOA alone was over $25,000, and a potential $40,000 special assessment loomed. They ultimately chose a single-family home in the Muirlands with no HOA at all, and the total carrying cost picture was dramatically different.
Something to keep in mind: California’s SB 326 balcony inspection requirements have been pushing condo HOA reserves and dues higher across San Diego. Older La Jolla condo buildings are especially affected.
Insurance Costs in La Jolla: The Line Item That Has Changed the Most
If there is one category where 2026 looks nothing like 2023, it is insurance. California’s homeowner’s insurance market continues to experience disruption, and coastal luxury properties in La Jolla feel the pressure acutely.
Here’s a realistic breakdown for a $3M to $5M La Jolla estate:
- Homeowner’s policy (HO-5 high-value form): $10,000 to $25,000 per year
- Earthquake coverage (CEA or private carrier): $5,000 to $15,000 per year
- Umbrella liability ($5M policy): $1,500 to $4,000 per year
- Flood insurance (if in a FEMA flood zone): $2,000 to $10,000 per year
Estimated total annual insurance: $15,000 to $50,000+
Properties near Torrey Pines or along canyon edges face elevated wildfire risk premiums. Some luxury homeowners have been pushed to the California FAIR Plan (the insurer of last resort) and then supplement with a Difference in Conditions policy. This approach works, but it is more expensive and requires more coordination.
What I tell my clients is this: get insurance quotes before you finalize your offer. In 2026, this is not a formality. It’s a budgeting necessity. With 18 years of experience in this market, I can say confidently that insurance has become one of the most significant variables in luxury ownership math.
Maintenance on a La Jolla Luxury Estate: The Silent Budget Eater
The coastal salt air, marine layer, and relentless sun in La Jolla accelerate wear on everything. Exterior paint, roofing materials, metal fixtures, and mechanical systems all have shorter lifespans here than in inland neighborhoods like Rancho Bernardo or Scripps Ranch.
Here’s what ongoing maintenance typically costs for a $3M to $5M property:
- Professional landscaping and grounds care: $12,000 to $36,000 per year
- Pool and spa maintenance: $3,600 to $7,200 per year
- HVAC servicing: $1,000 to $3,000 per year
- Pest control: $600 to $1,800 per year
- Exterior painting and salt air corrosion repair (amortized): $2,000 to $8,000 per year
- Window and glass cleaning (ocean view homes): $2,400 to $6,000 per year
- General repairs and handyman services: $5,000 to $15,000 per year
- Security system and monitoring: $1,200 to $4,800 per year
- Roof maintenance and inspections (amortized): $1,000 to $3,000 per year
Estimated total annual maintenance: $30,000 to $90,000
The industry rule of thumb is 1% to 2% of home value annually. For a $4M La Jolla home, that’s $40,000 to $80,000. Coastal properties tend to sit at the higher end of that range.
What Qualcomm Layoffs Mean for La Jolla Luxury Homeowners Right Now
I want to address something that is directly affecting this market. About two years ago, Qualcomm laid off roughly 10,000 employees, and right now in 2026, another round of AI-related workforce reductions appears to be underway. Many of these engineers own homes in La Jolla, Carmel Valley, Sorrento Valley, and surrounding communities.
If you’re in this position, carrying costs become the central question. Can you sustain $90,000 to $200,000 per year in non-mortgage expenses while navigating a career transition?
Here’s what I’d recommend if you are evaluating whether to sell:
- Run your monthly burn rate honestly. Add every line item above to your mortgage payment and see how many months of runway you have.
- Know the market timing. Homes priced above $2M in San Diego saw sales surge 8.5% year over year, and La Jolla single-family homes are averaging $3,545,011. Demand in the luxury segment remains strong, particularly from cash buyers (68% of luxury transactions).
- Prepare your home strategically. With my background in flips and remodels, I help sellers identify which improvements move the needle on value and which are wasted money. Sometimes a $15,000 investment in staging and cosmetic updates returns six figures. Check out my guide on pre-listing repairs worth doing in Del Cerro before you sell.
- Consider timing before the next wave. If additional Qualcomm layoffs materialize and multiple luxury listings hit simultaneously, you’ll be competing against neighbors in similar situations.
One client I worked with recently, an engineer in a similar corporate downsizing situation, was unsure whether to sell their Sorrento Valley home or hold and rent it out. After mapping out their full carrying costs, including $42,000 in annual taxes and $18,000 in insurance, it became clear that selling and relocating to a lower-cost market freed up over $8,000 per month. That clarity changed everything for their family’s next chapter.
Frequently Asked Questions
How much are total annual carrying costs on a $4M La Jolla home?
You should budget approximately $130,000 to $170,000 per year beyond your mortgage, covering property taxes around $48,000, insurance between $20,000 and $40,000, maintenance of $40,000 to $80,000, and any applicable HOA fees. The exact figure depends on property type and location within La Jolla.
Do all La Jolla homes have HOA fees?
No. Many single-family estates in La Jolla Farms, Muirlands, and La Jolla Shores have no HOA at all. Gated communities carry moderate fees, while luxury condos and oceanfront buildings can charge $1,200 to $2,500 or more monthly. Property type drives this cost entirely.
What is the property tax rate in La Jolla for 2026?
The effective property tax rate in La Jolla is approximately 1.20% of your purchase price. This combines the 1% Proposition 13 base rate with voter-approved bonds for schools and special districts. There are no significant Mello-Roos fees in most established La Jolla neighborhoods.
Is earthquake insurance required in La Jolla?
Earthquake insurance is not required by California law, but it is strongly recommended. California Earthquake Authority policies for a $3M to $5M home run approximately $5,000 to $15,000 annually with deductibles typically ranging from 5% to 25% of dwelling coverage.
How does the SALT cap affect La Jolla luxury homeowners?
For 2026, the SALT deduction is capped at $40,400. If you’re paying $48,000 in property taxes on a $4M home plus California income tax, you’ll exceed the cap quickly. This means a substantial portion of your property tax offers no federal tax benefit.
Why is homeowner’s insurance so expensive in La Jolla right now?
California’s insurance market continues experiencing disruption in 2026. Coastal luxury homes face elevated premiums due to wildfire proximity (near Torrey Pines and canyon edges), high rebuild costs, and carrier withdrawals from the California market. Some homeowners now rely on FAIR Plan coverage.
Are La Jolla carrying costs higher than Rancho Santa Fe or Del Mar?
La Jolla carrying costs are comparable to other coastal luxury markets, though La Jolla benefits from no Mello-Roos fees in most neighborhoods. Maintenance costs tend to be higher in La Jolla due to direct ocean exposure and salt air corrosion on building materials.
What maintenance costs are unique to coastal La Jolla homes?
Salt air corrosion accelerates wear on exterior paint, metal fixtures, roofing, and HVAC systems. Ocean-view window cleaning runs $2,400 to $6,000 annually. Exterior repainting cycles are shorter in La Jolla compared to inland San Diego neighborhoods.
Is 2026 a good time to sell a luxury home in La Jolla?
Luxury market conditions in San Diego remain favorable. Homes priced above $2M saw an 8.5% year-over-year sales increase, and 68% of luxury buyers are paying cash. If carrying costs are straining your budget due to a career transition, the current demand provides a strong selling window.
Should Qualcomm employees facing layoffs consider selling their La Jolla homes?
It depends on your financial runway. If you cannot sustain $90,000 to $200,000 in annual carrying costs during a prolonged job search, selling proactively while the luxury market is active gives you more control over timing and outcome than waiting until financial pressure forces a decision.
The Bottom Line
Owning a luxury home in La Jolla is about more than the purchase price or the mortgage payment. Your true carrying costs on a $3M to $5M estate will likely run between $90,000 and $200,000 annually, and in some cases more. Understanding what all costs are involved in buying a home provides a foundation, but luxury ownership adds unique layers.
Whether you’re buying into this market or evaluating whether to stay, these numbers deserve honest attention. With 275 five-star reviews and 18 years helping buyers and sellers across San Diego, I’ve learned that the clearest path forward always starts with clean information and a calm plan.
If you’re a Qualcomm engineer weighing your options, or a luxury buyer wanting to understand the full financial picture before committing, I’m here to walk through these numbers with you personally. Reach out to me, Scott Cheng, at 858-405-0002 or visit my office at 16516 Bernardo Center Dr. Ste. 300. Let’s get you clarity so you can move forward with confidence.
Have Questions About San Diego Real Estate?
Scott Cheng provides free, no-obligation consultations for buyers, sellers, and investors.
Schedule a Consultation