How Much Income You Need to Buy a Home in Normal Heights San Diego
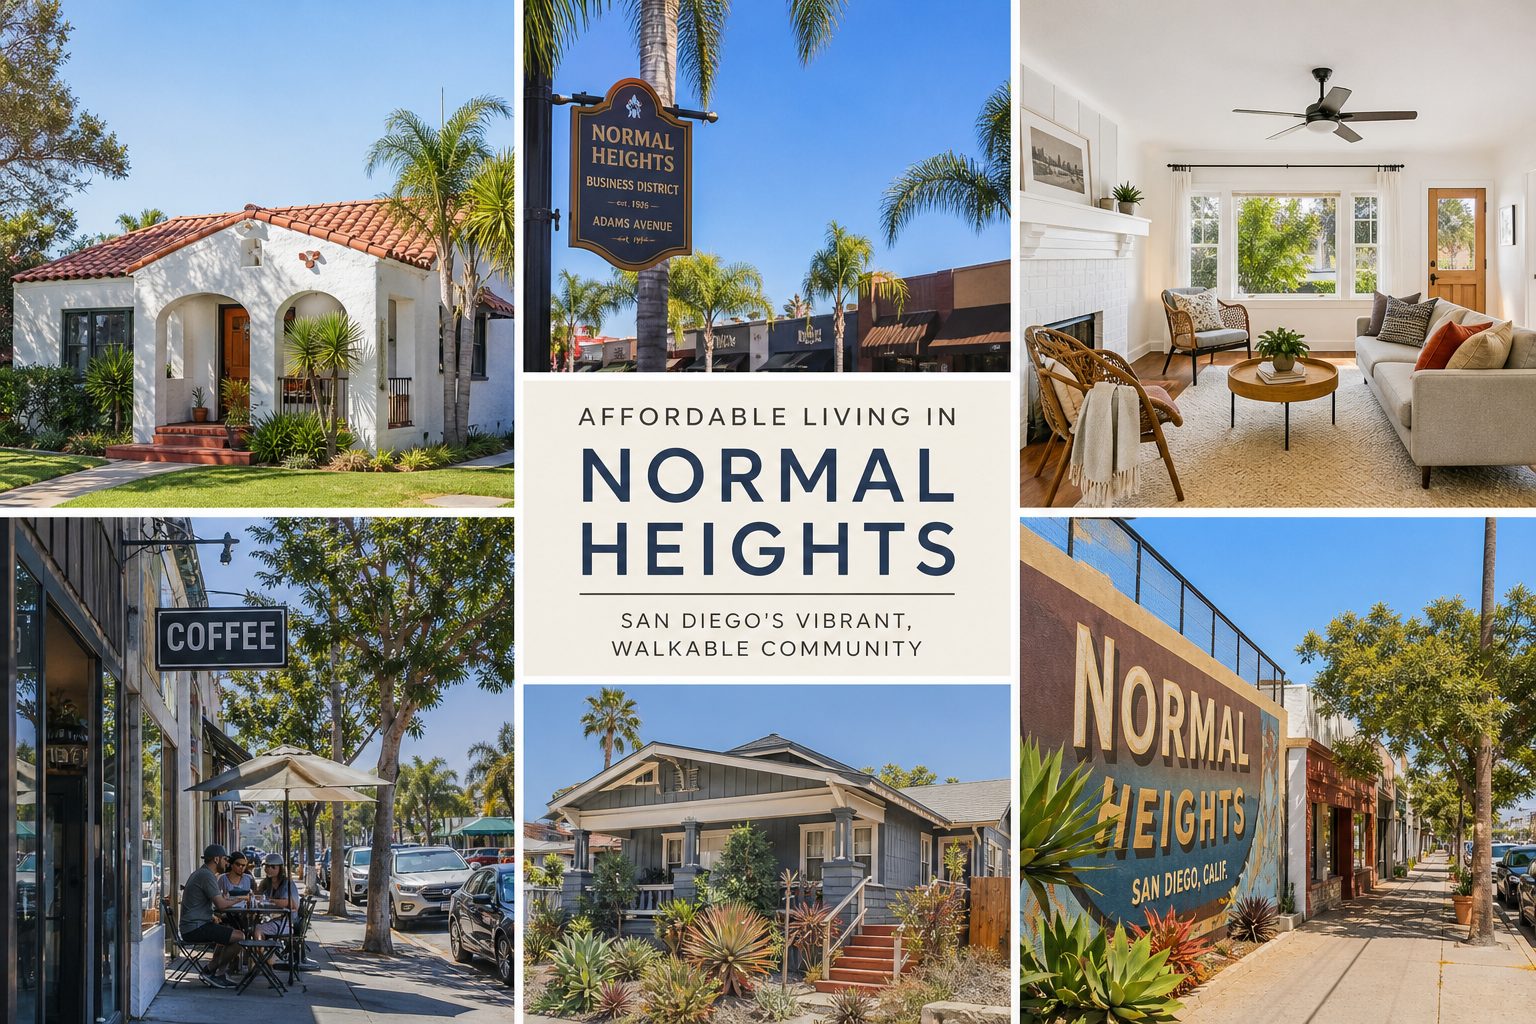
How much do I actually need to earn to afford a home in Normal Heights, San Diego in 2026, and what income, down payment, and debt-to-income ratio are lenders requiring right now?
For a median-priced Normal Heights home around $970,000 with 20% down, you need roughly $235,000 to $260,000 in gross household income, depending on your other debts and the DTI guideline your lender uses.
Why Normal Heights Affordability Matters Right Now in San Diego
If you have been browsing listings in Normal Heights and wondering whether the math actually works on your salary, you are not alone. This neighborhood sits right at the San Diego County median, with homes selling for about $970,000 as of summer 2026, per Redfin data. That is up roughly 9% over the past year.
Here is the tension: San Diego’s median household income is $104,321, according to Census data. A single-family home in Normal Heights requires somewhere between 1.5x and 2.5x that figure, depending on your down payment and existing debts. In my 18 years helping buyers navigate San Diego’s housing market, I have watched this gap widen steadily, and right now it is the single most common question I get from first-time buyers exploring neighborhoods like Normal Heights.
A cloudy mind can’t make decisions, so let me walk you through the real numbers, the actual lender requirements in 2026, and the strategies that can close the gap.
What a Normal Heights Home Actually Costs You Each Month in 2026
Before we talk income, you need to understand the full monthly picture. The purchase price is only the starting point. Your lender cares about the total monthly obligation, which includes principal, interest, property taxes, insurance, and potentially mortgage insurance.
As of September 2026, San Diego mortgage rates sit around 6.73% for a conventional 30-year fixed, per local lender rate surveys. That is down from where rates were hovering earlier in 2026 (the 6.6% to 7.1% band), but still meaningfully higher than the sub-6% dip we saw briefly in February 2026.
Here is what the monthly payment looks like at three common down payment levels on a $970,000 Normal Heights home:
- 20% down ($194,000 down, $776,000 loan) – Principal and interest around $5,033 per month, plus approximately $889 in property taxes (at roughly 1.1% of purchase price), plus about $150 in homeowner’s insurance. Total monthly PITI: approximately $6,072. No PMI required.
- 10% down ($97,000 down, $873,000 loan) – Principal and interest around $5,662, taxes $889, insurance $150, plus PMI around $364 per month. Total monthly: approximately $7,065.
- 3.5% FHA down ($33,950 down, $936,050 loan) – Principal and interest around $6,071, taxes $889, insurance $150, plus FHA mortgage insurance premium around $663. Total monthly: approximately $7,773.
What does that actually mean for your budget? At 20% down, you are paying more than $6,000 per month before you turn on a single light. That number needs context, so let’s talk about the income thresholds lenders are actually enforcing.
The Income Lenders Require for Normal Heights in 2026
Lenders use debt-to-income ratios (DTI) to determine whether you qualify. There are two numbers they look at:
- Front-end DTI (housing ratio): Your housing payment as a percentage of gross monthly income. Most conventional lenders cap this at 28% to 31%.
- Back-end DTI (total debt ratio): All monthly debts, including housing, car payments, student loans, and credit cards. Lenders typically cap this at 43%, though FHA allows up to 50% with strong compensating factors.
Here is where it gets real for Normal Heights buyers:
Scenario 1: $970,000 Median Home, 20% Down
- At 28% front-end DTI: you need approximately $260,229 in gross annual household income
- At 31% front-end DTI: approximately $235,045
- At 43% back-end DTI with no other debts: approximately $169,433
Scenario 2: $970,000 Home, 10% Down
- At 28% front-end: approximately $302,786 per year
- At 31% front-end: approximately $273,484
- At 43% back-end with no other debts: approximately $197,163
Scenario 3: $970,000 Home, 3.5% FHA Down
- At 28% front-end: approximately $333,129
- At 31% front-end: approximately $300,774
- At 43% back-end with no other debts: approximately $216,837
The critical insight here? Your existing debts dramatically change the math. A household earning $200,000 with zero car payments and zero student loans qualifies very differently than one earning $250,000 but carrying $1,500 per month in other obligations. Having closed over 275 transactions across San Diego, I can tell you that the back-end DTI is where most buyers hit their ceiling.
Down Payment Strategies That Change the Equation in Normal Heights
The down payment is the most flexible lever you have. And Normal Heights offers something that many San Diego neighborhoods do not: a real range of entry points.
While detached single-family homes carry that $970,000 median and range up to $1.2 million or higher, the condo market in Normal Heights starts significantly lower. One-bedroom condos list in the $355,000 to $399,000 range, and two-bedroom units sit closer to $430,000 to $550,000.
Here is what a $450,000 condo purchase looks like:
- 20% down ($90,000 down, $360,000 loan) – Total monthly PITI plus HOA (around $350): approximately $3,085. Income needed at 28% front-end DTI: approximately $132,214 per year.
- At 43% back-end with no other debt – Income needed: approximately $86,047.
That is a completely different conversation. For a dual-income couple earning $130,000 to $140,000 combined, a Normal Heights condo is within reach, and you are still in an eclectic urban village known for its historic bungalows and walkable, character-filled streets.
One more thing I always discuss with my clients: San Diego County’s conforming loan limit increased to $1,104,000 for 2026. That means most Normal Heights purchases, even at the higher end of single-family pricing, fall under the conforming threshold. You avoid jumbo loan territory, which comes with stricter requirements and higher rates (jumbo 30-year rates sit around 6.93% as of September 2026, per local rate data).
How Your Credit Score Shifts Normal Heights Affordability
Your credit score does not just determine whether you get approved. It determines what rate you pay, and in a market like Normal Heights, even a quarter-point difference translates to real money.
Based on current lender requirements in 2026:
- 740 or higher: You qualify for the strongest available rates, roughly 6.0% to 6.25%
- 700 to 739: Expect rates approximately 0.25% to 0.50% higher
- 660 to 699: Rates run 0.50% to 0.75% above the baseline
- Below 660: Conforming loan financing becomes difficult, and rates may exceed 7.5%
On a $776,000 loan (20% down on a $970,000 home), the difference between a 6.25% rate and a 7.0% rate is roughly $375 per month, or $4,500 per year. Over 30 years, that is $135,000 in additional interest.
What I tell my clients is simple: if you are six months away from buying and your score is in the 700 to 739 range, a targeted effort to push above 740 can save you more than almost any negotiation tactic on the purchase price itself. With 275 five-star reviews from past clients, rated 5 out of 5, the pattern I see repeatedly is that the buyers who prepare their finances three to six months in advance end up in the strongest position.
How Normal Heights Compares to Neighboring San Diego Neighborhoods
Understanding Normal Heights pricing in context helps you decide whether this neighborhood is the right target for your budget.
Normal Heights’ average home price over the past 24 months is approximately $1,149,018 based on 53 detached home sales, with an average price per square foot of $936 and a typical home size of about 1,316 square feet (per local CMA data as of February 2026).
Compare that to neighboring North Park, where the average over the same period runs $1,297,153 at $1,028 per square foot, per local market analysis. That is roughly $148,000 less for a similar style of home, similar era, similar character, and the same general central San Diego lifestyle.
Most Normal Heights homes feature two bedrooms and two-and-a-half bathrooms, with 1,000 to 1,400 square feet of living space. Two-bedroom bungalows, the most common entry-level single-family option here, are currently pending in the $899,000 to $949,000 range.
For context on what that means for income: a $925,000 bungalow with 20% down ($185,000 down, $740,000 loan) runs approximately $5,825 per month in total PITI. At 28% front-end DTI, that requires about $249,643 in annual income.
Frequently Asked Questions
What is the minimum income to buy a house in Normal Heights San Diego in 2026?
For a median-priced single-family home around $970,000 with 20% down, you need approximately $235,045 to $260,229 in gross annual income, depending on whether your lender uses 28% or 31% front-end DTI. With a smaller down payment, the income requirement climbs above $270,000. Condos starting around $355,000 to $450,000 offer a lower threshold, with income requirements closer to $86,000 to $132,000.
What DTI ratio do San Diego lenders require in 2026?
Most conventional lenders require a front-end (housing) DTI of 28% to 31% and a back-end (total debt) DTI below 43%. FHA loans allow up to 50% back-end DTI when borrowers have compensating factors like strong cash reserves and minimal payment shock. Your existing monthly debts, including car loans and student loans, directly reduce how much housing payment you qualify for.
How much down payment do I need for a Normal Heights home?
Conventional loans require as little as 3% down (about $29,100 on a $970,000 home) for buyers with 680-plus credit scores. FHA requires 3.5% (about $33,950). VA-eligible buyers can put $0 down with no PMI. However, anything below 20% triggers mortgage insurance, which adds $364 to $663 per month to your payment and raises the income you need.
Are Normal Heights condos more affordable than houses?
Significantly. One-bedroom condos in Normal Heights list in the $355,000 to $399,000 range as of late 2026, while single-family homes range from about $700,000 to $1.2 million. A $450,000 condo with 20% down requires roughly $132,214 in annual income at 28% front-end DTI, compared to over $235,000 for a single-family home.
What mortgage rate should I expect in Normal Heights in 2026?
As of September 2026, conventional 30-year fixed rates average around 6.73%, with FHA at 6.43% and VA at 6.13%, per local San Diego rate surveys. Fannie Mae projects rates could fall to roughly 5.9% by year-end 2026. Buyers with credit scores above 740 access the strongest rates, typically 6.0% to 6.25%.
Is Normal Heights cheaper than North Park for homebuyers?
Yes. Normal Heights’ average home price over the past 24 months is approximately $1,149,018, compared to $1,297,153 in North Park, per local CMA data as of February 2026. That is roughly $148,000 less for homes of similar vintage and character, with comparable walkability and neighborhood culture.
Do I need a jumbo loan to buy in Normal Heights San Diego?
Most likely not. San Diego County’s conforming loan limit for 2026 is $1,104,000, which covers the vast majority of Normal Heights purchases. Only properties priced above approximately $1,380,000 (assuming 20% down) would push into jumbo territory, where rates are higher at around 6.93%.
How does FHA compare to conventional for Normal Heights buyers?
FHA allows lower credit scores (580 minimum) and just 3.5% down, but adds a mortgage insurance premium of roughly 0.85% of the loan amount annually. On a $936,050 FHA loan, that is about $663 per month. Conventional loans with 20% down avoid mortgage insurance entirely. FHA works for buyers who need a lower down payment, but the higher monthly cost raises the income threshold.
What monthly payment should I expect on a Normal Heights home?
On a $970,000 home with 20% down at approximately 6.73%, expect about $6,072 per month for principal, interest, taxes, and insurance. With 10% down, that rises to about $7,065 including PMI. With 3.5% FHA, it reaches approximately $7,773 including the FHA mortgage insurance premium.
Can a single income qualify for a Normal Heights home in 2026?
For a condo in the $355,000 to $450,000 range, a single income of $86,000 to $132,000 can qualify depending on the DTI standard used and your existing debts. For a median single-family home at $970,000, a single income would need to reach $170,000 to $260,000, which is achievable for some San Diego professionals in tech, biotech, and healthcare, but dual incomes remain the more common path to qualification.
The Bottom Line on Affording a Normal Heights Home in 2026
Normal Heights gives you central San Diego character and walkability at a meaningful discount to North Park, but the income bar is still high. A detached home at the median demands roughly $235,000 to $260,000 in household income with 20% down, while a condo entry point brings that closer to $86,000 to $132,000.
The variables you can control matter enormously: your credit score, your existing debts, your down payment size, and your loan product selection. Each one shifts the math by tens of thousands of dollars in annual income required.
If you want a calm, clear plan to figure out exactly where you stand, I am here to help. As an Associate Broker at REAL Brokerage with 18 years serving San Diego County and over 275 closed transactions, I walk buyers through this math every week. I also provide a complimentary attorney review of contracts and disclosures, covered by me, even if escrow cancels. Reach me at 858-405-0002 or through Scott Cheng San Diego Realtor to start mapping your path into Normal Heights.
Have Questions About San Diego Real Estate?
Scott Cheng provides free, no-obligation consultations for buyers, sellers, and investors.
Schedule a Consultation